

json
{ “Title”: “Best Ways to Borrow Money Against Your Car”, “MetaDescription”: “Compare the top 5 ways to borrow money against your car in 2026. See loan amounts, APR ranges, and what to check before you apply.”, “article_html”: “
Your car might be your fastest path to cash right now. If you own it outright, you can use the title as collateral and walk away with funds the same day, often without a credit check. Here are the five best options to borrow money against your car, plus what to look for before you sign anything.
nn
1. EZ Car Title Loans (Our Top Pick) , Fast, Transparent Car Title Loans
n
EZ Car Title Loans is a loan-matching platform that connects vehicle owners with licensed title lenders across multiple US states. It does not lend directly, which actually works in your favor: instead of being stuck with one lender’s terms, you get competing offers you can compare before committing.
n
Loan amounts run from $500 to $55,000, with APR between 5.99% and 35.99% for qualifying borrowers. Repayment terms stretch from 91 days up to 70 months, and there are no prepayment penalties if you pay off early. That APR range is one of the most transparent disclosures in this space, where many competitors simply don’t publish their rates.
n
The application takes about 10 minutes online. Lenders evaluate your vehicle’s equity as the primary factor, so past credit problems don’t automatically close the door. You keep driving your car throughout the loan term while the lender holds a lien on the title. Once you pay off the balance, the lien is released and the title comes back to you.
n
EZ Car Title Loans currently serves borrowers in Arizona, Texas, Nevada, Louisiana, Wisconsin, and other states. Coverage and lender availability vary, so check eligibility for your state before applying. As a matching platform, approval is not guaranteed , each lender in the network has its own underwriting rules.
n
If you want fast approval with transparent terms and the ability to keep driving, same-day title loan funding through EZ Car Title Loans is the strongest starting point on this list.
nn
2. Title Loans Direct , Nationwide Network with Flexible Terms
nnnn
Title Loans Direct operates as a broker-style network connecting borrowers to a wide pool of state-licensed lenders. The pitch is geographic reach: the network covers most US states where title lending is legal, making it useful if you live somewhere smaller platforms don’t serve.
n
The application is fully online. You enter your vehicle details, and the system routes your request to lenders that operate in your state. Because multiple lenders see your application at once, you may receive several offers with different terms, which gives you negotiating room.
n
One thing worth knowing: broker networks like this sometimes pass your contact information to multiple lenders simultaneously. That can mean a flood of calls and texts after you apply. If that’s a concern, read the privacy policy before submitting your details.
n
Flexible terms are the main draw here. Some borrowers report finding lenders willing to extend repayment windows beyond the standard 30-day title loan structure, which matters a lot if you need more time to pay back without rolling over. Rollover fees are a known trap in this industry, so any lender offering a longer initial term is worth a closer look.
n
The honest caveat: because Title Loans Direct is a network, the quality of individual lenders varies. Always verify that the lender you’re matched with is licensed in your state before signing. The Consumer Financial Protection Bureau (CFPB) maintains resources on what licensed lenders are required to disclose, including the full APR in writing before you sign.
nn
3. FastCash Car Loans , Quick Funding for Urgent Needs
n
FastCash Car Loans targets borrowers who need money fast. The focus is speed: the application is short, the approval process is simplified, and funding can happen within 24 hours for qualified applicants.
n
The model is similar to a direct storefront lender. You submit your vehicle information and ID, a representative appraises the car remotely or in person, and if approved, funds arrive via direct deposit or check. Physical pickup locations are available in some markets for borrowers who want cash the same day rather than waiting for an ACH transfer to clear.
n
FastCash positions itself toward borrowers with urgent, short-term needs, medical bills, a missed rent payment, a car repair that can’t wait. The loan amounts tend to be on the lower end of the spectrum, which keeps the process simple but limits how much you can access if your vehicle has significant equity.
n
APR and specific terms are not publicly listed, which is a transparency gap worth noting. Our research found that only one provider in this space, Freedom Title Loans in Idaho, openly advertises a 300% APR and a $25,000 loan ceiling. That kind of disclosure is rare, and its absence elsewhere means you need to ask for the full APR in writing before you agree to anything. A monthly fee quoted as 25% translates to 300% APR annually, so the math matters.
n
FastCash works best when speed is the priority and the loan amount you need is modest. If you’re borrowing against a high-value vehicle and want to maximize what you receive, a platform with a higher loan ceiling is a better fit.
nn
nn
4. Auto Title Funding , Competitive Rates for High-Value Vehicles
nn nn
Auto Title Funding specializes in borrowers with newer or higher-value vehicles. Where some lenders cap loans at $10,000 or $15,000, this type of lender is built to handle vehicles worth significantly more, trucks, SUVs, luxury sedans, and work vehicles that carry real equity.
n
The qualification logic is straightforward: the more your car is worth, the more you can borrow. Most lenders in this category offer between 25% and 50% of the vehicle’s appraised market value. So a truck appraised at $40,000 could support a loan of $10,000 to $20,000, depending on the lender’s specific formula and your state’s regulations.
n
Rates at lenders focused on high-value vehicles can be more competitive than standard title loan rates, partly because the collateral reduces the lender’s risk. A larger loan secured by a $40,000 truck is a different risk profile than a $1,500 loan on a 2009 sedan. That risk difference sometimes shows up as a lower APR, though it’s not guaranteed.
n
If your vehicle is newer and in good condition, it’s worth getting a quote from a lender that specifically handles higher loan amounts rather than defaulting to the first platform you find. The difference in what you’re offered can be significant, and the loan-to-value ratio varies more than most borrowers expect.
n
One caveat: lenders handling large loans against high-value vehicles may require more documentation, including proof of insurance and sometimes a spare key. Factor that into your timeline if you’re in a hurry. Also confirm whether your state caps title loan amounts, since some do regardless of vehicle value.
nn
5. SecureRide Loans , Simple Online Application Process
nn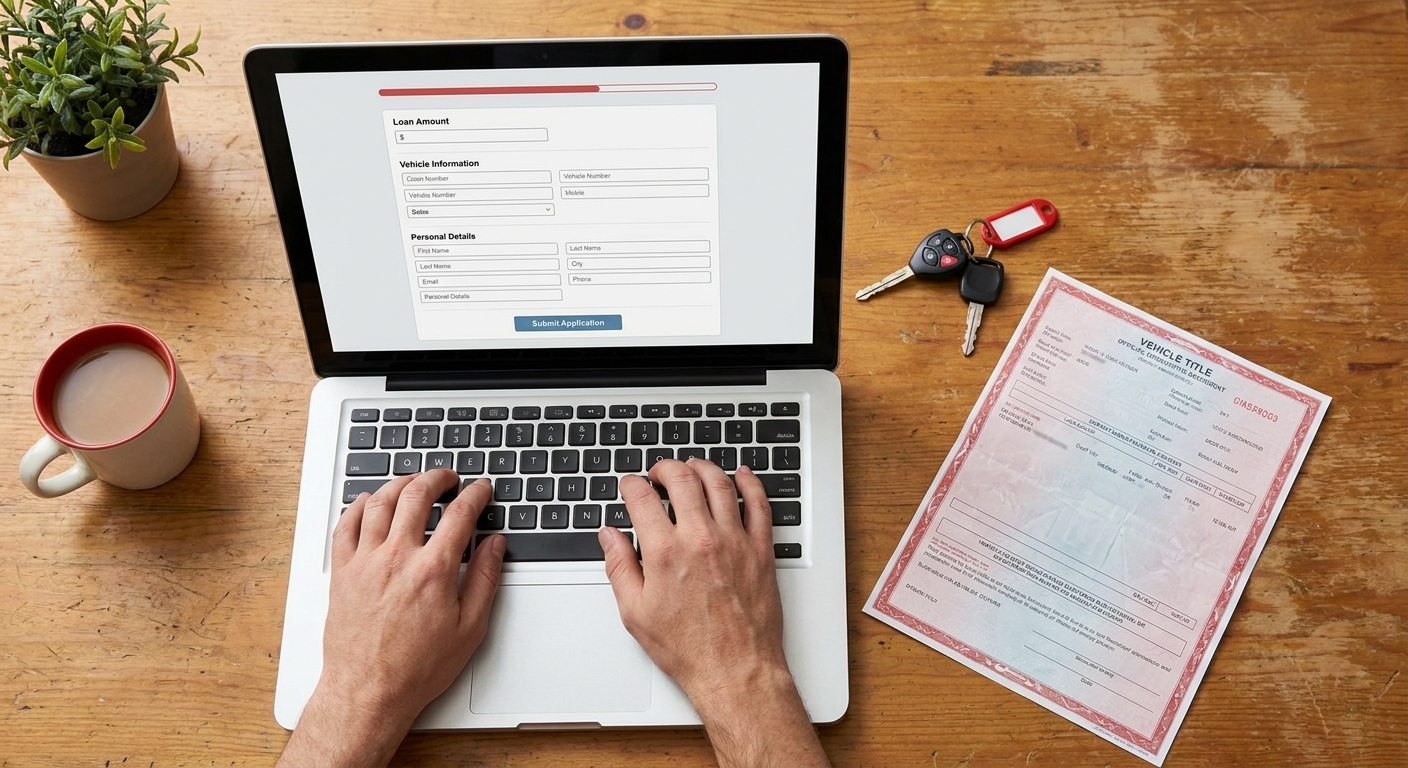 nn
SecureRide Loans is built around simplicity. The entire process lives online, from the initial application to document upload to funding. There’s no storefront visit required, no in-person appraisal in most cases, and no stack of paperwork to fill out by hand.
n
The application asks for basic vehicle details: year, make, model, mileage, and condition. You upload a photo of your title and a government-issued ID. A remote appraiser reviews the submission and returns a loan offer, typically within a few hours. If you accept, funds move via ACH direct deposit, usually the next business day.
n
This process suits borrowers who are comfortable handling everything digitally and don’t need cash in hand the same afternoon. If you can wait until the next morning, the online-only model is genuinely convenient. You can apply at midnight if that’s when you have time.
n
When you borrow against your car this way, the lender registers a temporary lien on your vehicle’s title with your state’s motor vehicles department. You remain the registered owner and keep driving. Once the loan is paid in full, the lien is released. This is standard practice across all title loan structures, as explained in the definition of a secured loan, where the debt is backed by an asset the lender can claim if repayment fails.
n
The main limitation with fully online lenders is that same-day cash is harder to guarantee. ACH transfers take time. If you need physical cash today, a local storefront lender or a platform with in-person pickup options is a better fit. SecureRide works best for borrowers with a day’s flexibility and a preference for doing everything from their phone.
nn
What to Look For When Choosing a Car Title Loan
n
Not every lender is worth your time. A few things separate a fair deal from a trap.
n
APR disclosure.The annual percentage rate is the only number that lets you compare loans fairly. Monthly fee percentages hide the real cost. A 25% monthly fee is 300% APR. Ask for the APR in writing before you sign. Federal law requires lenders to disclose it, so any lender that refuses is a red flag.
n
State licensing.Title lending laws vary sharply by state. Some states prohibit title loans entirely. Others cap loan amounts or require specific disclosures. Confirm the lender is licensed in your state before you hand over your title. Your state’s financial regulator maintains a list of licensed lenders.
n
Rollover policy.If you can’t pay in 30 days, does the loan automatically roll over with added fees? Rollovers are how many borrowers end up paying far more than they borrowed. Ask specifically about this before signing.
n
Loan-to-value ratio.Most lenders offer 25% to 50% of your vehicle’s current market value. Know your car’s value before you apply. If the offer feels low, it may be, and you can negotiate or shop elsewhere.
n
Repossession risk.Defaulting on a title loan means the lender can repossess your vehicle. This is not a theoretical risk. If you’re uncertain about repayment, act early: contact the lender before you miss a payment, not after. Many lenders prefer to work out an extension rather than go through the cost and hassle of repossession.
nn
nn
Lenders that don’t publish APR or loan terms upfront are worth approaching with caution. Transparency about rates is one of the clearest signals of a lender operating in good faith. If you’re also managing other vehicle costs, knowing your minimum car insurance requirements in your state is worth checking alongside your loan terms, since some lenders require proof of active coverage before approving.
nn
Quick Comparison of the 5 Options
n
nn
FAQ
nn
How much can I borrow against my car?
n
Most lenders offer between 25% and 50% of your vehicle’s current market value. A car worth $10,000 might support a loan of $2,500 to $5,000. Platforms like EZ Car Title Loans connect borrowers with lenders offering up to $55,000 for high-value vehicles. The exact amount depends on the car’s year, make, model, mileage, and condition at the time of appraisal.
nn
Do I need good credit to borrow money against my car?
n
No. Title loans are secured by your vehicle’s equity, so lenders focus on what your car is worth rather than your credit score. Borrowers with poor or no credit history can still qualify if the vehicle has enough equity and the state permits title lending. Approval is not guaranteed, but bad credit alone is rarely the sole disqualifier when the collateral is solid.
nn
Can I keep driving my car while repaying a title loan?
n
Yes. You keep driving your vehicle throughout the loan term. The lender holds a lien on the title, not the car itself. Once you pay off the balance in full, the lien is released and the title returns to you. This is one of the main usable differences between a title loan and a pawn loan, where you’d hand over the physical item.
nn
What documents do I need to apply?
n
You typically need a lien-free vehicle title in your name, a government-issued photo ID, proof of income (pay stubs, bank statements, or benefit letters), and proof of residence. Some lenders also ask for proof of insurance or a spare key. Having these ready before you start the application speeds up the process significantly.
nn
What happens if I can’t repay a car title loan?
n
If you default, the lender has the right to repossess your vehicle. Repossession is costly and slow, so most lenders prefer to work out an extension before taking that step. If you’re struggling to pay, contact the lender early. Acting before a missed payment gives you more options than waiting until you’re already in default.
nn
Are car title loans legal in every state?
n
No. Title lending laws vary sharply by state. Some states prohibit them entirely, while others cap loan amounts, fees, or terms. Before applying, confirm that title loans are legal where you live and that the lender you choose is licensed by your state’s financial regulator. A lender operating without a state license is a serious warning sign.
nn
Conclusion
n
If you need to borrow money against your car and want transparent terms, a wide lender network, and the ability to keep driving, start with EZ Car Title Loans. The published APR range and multi-state coverage make it the easiest place to compare real offers without guessing. Visit ezcartitleloans.com to check your eligibility and get a free quote today.


