

Yes, you can get a title loan with bad credit. Most title lenders look at your vehicle’s value more than your credit score, so a low score doesn’t automatically disqualify you. But not all options are equal. Here are the six best routes to consider, starting with the one that makes the most sense for most borrowers.
1. EZ Car Title Loans , Best Starting Point for Bad Credit Borrowers
EZ Car Title Loans is an online platform that connects vehicle owners with licensed title loan lenders across the US. It’s not a direct lender, which means it shops your application across multiple licensed partners to find a fit, even if your credit history is rough.
The platform evaluates your vehicle’s equity as the main qualification factor, not a traditional credit score threshold. A borrower who can’t get approved at a bank may still qualify based on verified vehicle value alone. You keep driving your car throughout the repayment period, and the lender holds a lien on the title until the loan is paid off.
Loan amounts range from $500 to $55,000, with APR rates between 5.99% and 35.99% for qualifying borrowers. Repayment terms run from 91 days to 70 months, and there are no prepayment penalties. Applications can be completed online in minutes, with same-day approval available for eligible borrowers.
The transparency is a real plus. EZ Car Title Loans publishes its terms clearly, so you won’t hit surprise fees mid-process. Both online and in-person support options are available depending on your state.
The main caveat: APR and available terms vary by lender and state. Not every borrower will qualify for the lowest rates advertised. Always read the full loan agreement before signing. If you want same-day cash using your car’s equity while keeping the wheels, EZ Car Title Loans is the clearest first stop.
2. Title Loans Through Local Credit Unions , Lower Rates for Members
Credit unions are nonprofit, member-owned institutions. That structure often translates to lower interest rates and more flexibility than a traditional bank, especially if you’re rebuilding your credit.
Most credit unions don’t offer title loans in the traditional sense, but they do offer secured personal loans and auto equity loans that work similarly. You use your paid-off vehicle as collateral to borrow against its value. The key difference from a typical title loan: credit unions run a credit check and verify income, and they usually cap rates well below the 300% APR common in the title loan industry.
lines, credit unions typically accept FICO scores as low as 580 to 600 for secured loans, and they often review applications manually rather than relying on automated rejection systems. That human review can help borrowers with medical debt, gaps in employment, or non-traditional income sources.
You do need to become a member first. Some credit unions serve specific employers, geographic areas, or community groups, so not everyone qualifies. But many have open membership pathways that require only a small deposit to join.
The trade-off is speed. Credit union approvals typically take longer than same-day title loan platforms. If your emergency needs cash within 24 hours, a credit union may not move fast enough. But if you have a few days and want a lower-cost option, it’s worth calling your local branch first.
3. Online Title Loan Marketplaces , Comparing Multiple Lenders at Once
Online title loan marketplaces let you submit one application and receive offers from several licensed lenders simultaneously. The appeal is obvious: you see multiple rates side by side instead of applying separately to each lender.
These platforms work best for borrowers who want to comparison shop without taking multiple hard credit inquiries. Many marketplaces use a soft pull first, so your credit score isn’t dinged just for checking options.
The usable benefit is real. Title loan rates can vary widely between lenders, even for the same vehicle and loan amount. One lender might offer a 30-day term at a high monthly fee; another might offer a 6-month installment structure at a lower rate. Seeing both at once helps you make a smarter call.
The Federal Trade Commission advises borrowers to use the APR as the primary comparison tool when evaluating any short-term loan. That single number accounts for all fees and charges, not just the stated interest rate. When comparing marketplace offers, sort by APR first, not monthly payment.
One honest limitation: marketplaces earn money by connecting you to lenders, which means they’re incentivized to show you offers even if none are particularly good for your situation. Read every offer carefully. A lower monthly payment with a longer term often means you pay far more in total. Don’t let the interface pressure you into a quick decision.
4. State-Licensed Title Lenders , Knowing Which States Allow Title Loans
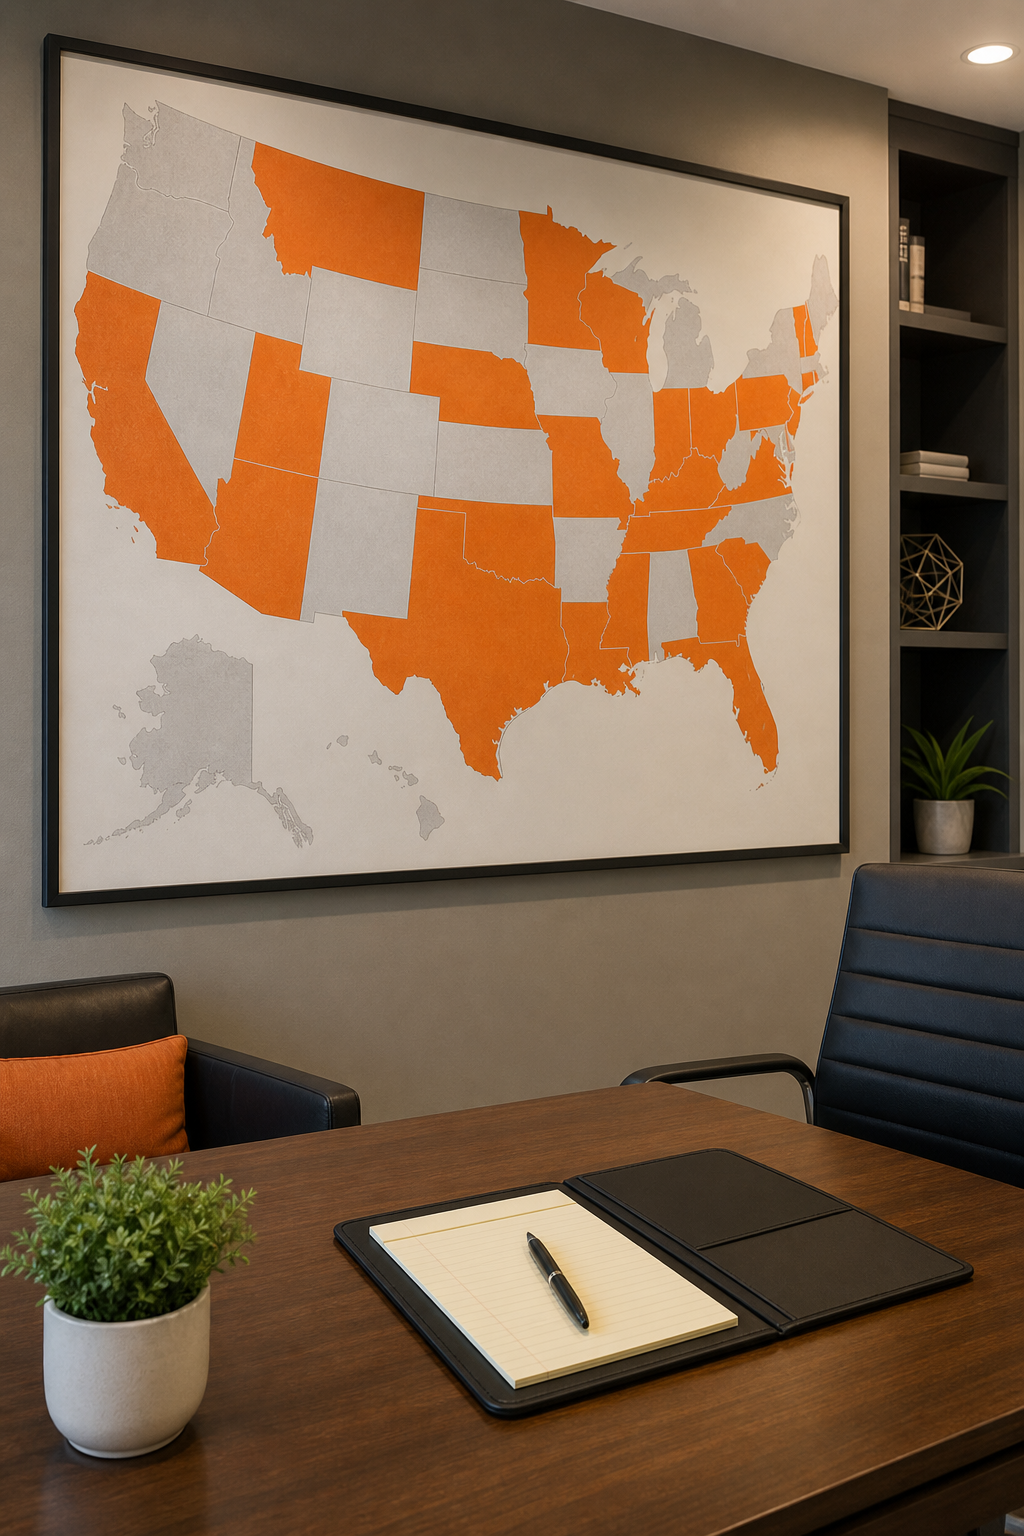
Before you apply anywhere, check whether title loans are even legal in your state. This step matters more than most people realize.
According to research published by the Center for Responsible Lending, high-cost vehicle title lending is currently prohibited in 33 US states and the District of Columbia. Despite that, the FDIC found in its National Survey of Unbanked and Underbanked Households that residents in almost every state had used title loans, suggesting some lenders operate in prohibited states through regulatory workarounds.
If you live in a state where title loans are legal, working with a state-licensed lender is the safest path. Licensed lenders must disclose the full APR, follow state-mandated rate caps, and comply with repossession rules that protect borrowers. Unlicensed lenders face none of those constraints.
How do you confirm a lender is licensed? Check your state’s Department of Financial Institutions or Division of Consumer Finance website. Most states maintain searchable databases of licensed lenders. If a lender can’t be found in that database, don’t borrow from them regardless of how convenient their process looks.
States that generally permit title loans include Texas, Missouri, Florida, Nevada, and Arizona, among others. States that prohibit or heavily restrict them include New York, New Jersey, Pennsylvania, and North Carolina. Laws change, so verify current status directly with your state regulator before applying. EZ Car Title Loans operates within licensed lending networks and can help you understand what’s available in your state.
If title loans aren’t available where you live, the options in sections 2 and 5 of this list may still be accessible to you.
5. Pawnshop Title Loans , A Last Resort Option With High Risk
Some pawnshops offer a version of a title loan called a title pawn, most commonly in states like Georgia where the product is separately regulated. The mechanics are similar to a standard title loan: you hand over your vehicle title as collateral and receive cash. You keep the car as long as you make payments.
The major appeal for bad credit borrowers is the low barrier. Pawnshops rarely run credit checks. If you have a clear title and a working vehicle, approval is usually fast. That speed and accessibility is real.
But pawnshop title loans tend to carry the highest costs of any option on this list. Monthly fees of 25% are common, which works out to around 300% APR. Terms are typically 30 days, and rolling over the loan adds new fees each cycle. The debt can compound fast.
There’s also a usable complication: pawnshops are physical locations, so availability is hyperlocal. A pawnshop in one county might offer this product; the one across town might not. You can’t comparison shop the way you can with an online platform.
If you’re considering this route because you’ve been turned down elsewhere, it’s worth trying EZ Car Title Loans first. The platform connects borrowers with licensed lenders who may approve applications that traditional lenders decline, often at better terms than a pawnshop title pawn.
Use pawnshop title loans only if you’re certain you can repay in full within the short term. Rolling over even once doubles your fees and makes exit much harder.
6. Title Loan Refinancing , If You Already Have a Loan and Want Better Terms
If you already have a title loan with high fees and you’re struggling to keep up, refinancing is worth exploring before you default.
Refinancing means taking out a new title loan to pay off your existing one. The goal is a lower interest rate, a longer repayment term, or both. A longer term reduces your monthly payment, which can relieve immediate pressure. A lower rate reduces the total cost over the life of the loan.
To qualify for refinancing, you generally need to be current on your existing payments. Lenders also require that your vehicle is worth more than the outstanding loan balance, since the car is still the collateral. A salvage or rebuilt title usually disqualifies you with most lenders.
One thing to watch: refinancing extends how long you’re in debt. Each new loan restarts the clock. If you refinance repeatedly, you may pay more in total interest even if each individual payment looks smaller. Refinancing makes sense when it helps you avoid default, not as a way to delay paying down the principal indefinitely.
Some borrowers also try renegotiating with their current lender before refinancing with a new one. A loan modification, which adjusts your rate or payment schedule without a full new application, can sometimes achieve similar results with less paperwork. Call your lender and ask directly whether any modification options exist. Many will work with you if you reach out early, before you’ve missed payments.
Major home expenses sometimes drive the urgency behind refinancing decisions. Someone dealing with a large repair bill, for example, might find it helpful to read a breakdown of whole-house repipe costs to understand what they’re actually financing before committing to new loan terms.
What to Look For When Choosing a Title Loan With Bad Credit
Once you know your options, use these five criteria to evaluate any lender before you sign anything.
Under federal law, every lender must disclose the loan’s APR and total finance charge in writing before you sign. This requirement applies to title loans just as it does to other credit products. If a lender resists providing that information upfront, walk away.
The Consumer Financial Protection Bureau has also established rules around short-term lending that give borrowers certain protections, particularly around payment withdrawal attempts after failed transactions. Knowing these rights matters when something goes wrong mid-repayment.
Bad credit borrowers are especially vulnerable to predatory terms because options feel limited. But limited options don’t mean no use. A lender willing to show you the full APR, confirm their state license, and explain repossession procedures clearly is worth far more than one offering fast cash with vague terms.
Frequently Asked Questions
Can I get a title loan with a 500 credit score?
Yes, many title lenders approve borrowers with scores well below 600 because approval depends primarily on your vehicle’s value, not your credit score. That said, a very low score may affect which lenders will work with you and what rate you receive. EZ Car Title Loans connects borrowers with licensed lenders who evaluate vehicle equity as the main factor, making approval possible even with a 500 score.
What documents do I need to apply for a title loan?
Most lenders require a clear vehicle title in your name, a government-issued photo ID, proof of insurance, and sometimes proof of income or residency. Having these documents ready before you apply speeds up the process considerably. Some lenders may also ask for a duplicate set of keys, particularly pawnshop-style title lenders.
Will applying for a title loan hurt my credit score?
Many title lenders skip the credit check entirely, which means no hard inquiry and no impact on your score. If a lender does run a hard pull, it may lower your score by a few points temporarily. Always ask upfront whether the lender does a hard or soft credit check so you can avoid surprises during the application.
What happens if I can’t repay my title loan on time?
If you miss payments, the lender can repossess your vehicle. In some states, lenders can keep the full sale proceeds even if the car sells for more than you owe. Contact your lender before missing a payment. Many will work out a modified payment plan or extension if you act early. Ignoring the problem makes repossession far more likely.
Are title loans available in every US state?
No. Title loans are prohibited or heavily restricted in roughly 33 states and Washington DC. States like Texas, Florida, and Nevada permit them; states like New York and Pennsylvania do not. Always verify your state’s current rules through your state financial regulator before applying. EZ Car Title Loans can help you check what’s available in your state.
How much can I borrow with a car title loan?
Loan amounts typically range from 25% to 50% of your vehicle’s current market value. On a $10,000 car, that means roughly $2,500 to $5,000. Some platforms like EZ Car Title Loans can facilitate loans up to $55,000 for higher-value vehicles. The exact amount depends on the lender, your vehicle’s condition, and the state you’re in.
Conclusion
Getting a title loan with bad credit is genuinely possible, and EZ Car Title Loans is the most usable first step for most US borrowers. The platform connects you with licensed lenders, keeps terms transparent, and lets you keep driving your vehicle while you repay. Before you apply anywhere, confirm the lender is state-licensed, get the full APR in writing, and make sure the repayment term is realistic for your budget. Start your application at EZ Car Title Loans to see what you qualify for today.


