

json
{ “Title”: “Title Loan No Credit: Eligibility Explained”, “MetaDescription”: “Learn the real eligibility requirements for a title loan with no credit check, how state laws affect your options, and how EZ Car Title Loans can help you qualify.”, “article_html”: “
You can qualify for a car title loan even with no credit history at all. The loan is secured by your vehicle, so lenders focus on what your car is worth, not what your credit report says. Here’s what actually determines eligibility, how state laws shape your options, and what to watch out for before you sign anything.
nn
Understanding Title Loans and Credit Checks
A title loan is a short-term secured loan. You hand over your vehicle title as collateral, the lender holds a lien on it while you repay, and you keep driving your car the whole time. Because the loan is backed by physical collateral, most lenders skip the traditional credit check entirely.
That’s the core mechanic. Unlike a personal loan, where a lender is essentially betting on your payment history, a title lender is betting on your car’s resale value. If you default, they can repossess and sell the vehicle to recover their money. That security is why credit score is largely irrelevant to the approval decision.
Many title lenders do not run a hard credit inquiry when you apply. That means applying won’t temporarily knock points off your score the way a bank loan application would. It also means a title loan won’t help you build credit, since lenders typically don’t report payments to the credit bureaus either.
The trade-off is cost. Monthly rates can be high and vary widely by lender and state; borrowers should review the terms carefully. A $500 loan paid off in 30 days can cost significantly more once fees and interest are added. The secured structure makes approval easy. It makes repayment expensive.
One more thing worth knowing: if you can’t repay on time and roll the loan over into a new one, fees stack fast. That cycle is how borrowers end up owing far more than they originally borrowed. Go in with a clear repayment plan, not just a plan to get the cash.
Disclaimer: EZ Car Title Loans is not a direct lender and does not set APRs or loan terms. Rates, fees, and eligibility vary by lender and state. Borrowers should carefully review any loan agreement and understand the risk of vehicle repossession on default.
Key Eligibility Factors Beyond Credit Score
nn nn
Since credit score is off the table, lenders look at a different set of factors. These are the things that actually determine whether you qualify and how much you can borrow.
nn
Vehicle Ownership and Title Status
nn
Your car title must be in your name and free of liens. That means no outstanding auto loan balance against the vehicle. If you’re still making payments to a bank or finance company, you don’t fully own the car yet, and most standard title loan programs won’t approve you. The title has to be clear.
nn
The vehicle itself needs to be in working condition. Lenders assess make, model, year, mileage, and overall condition to determine current market value. That value drives the loan amount. Most lenders offer between 25% and 50% of your vehicle’s assessed value, though some states allow up to 100% loan-to-value.
nn
Proof of Income
nn
You don’t need a traditional paycheck. Lenders want to know you can repay, and that can be shown through a wide range of income sources. Pay stubs work, but so do Social Security benefit letters, pension statements, disability awards, bank statements showing regular deposits, and even settlement payments ordered by a court. The point is demonstrating a steady, verifiable cash flow.
nn
Age and Identification
nn
You must be at least 18 years old. A valid government-issued photo ID is required in every state. Some lenders also ask for proof of residency, like a utility bill or lease agreement, and current vehicle registration in your name.
nn
Insurance and References
nn
Many lenders require proof of at least minimum liability insurance on the vehicle. Some ask for personal references. These requirements vary by lender and by state, so it’s worth confirming the exact list before you apply.
nn
If you’re wondering whether your specific situation qualifies, the breakdown of credit score requirements for Texas title loans shows clearly that collateral, not credit history, is what lenders actually evaluate.
nn
nn
State-by-State Eligibility Overview
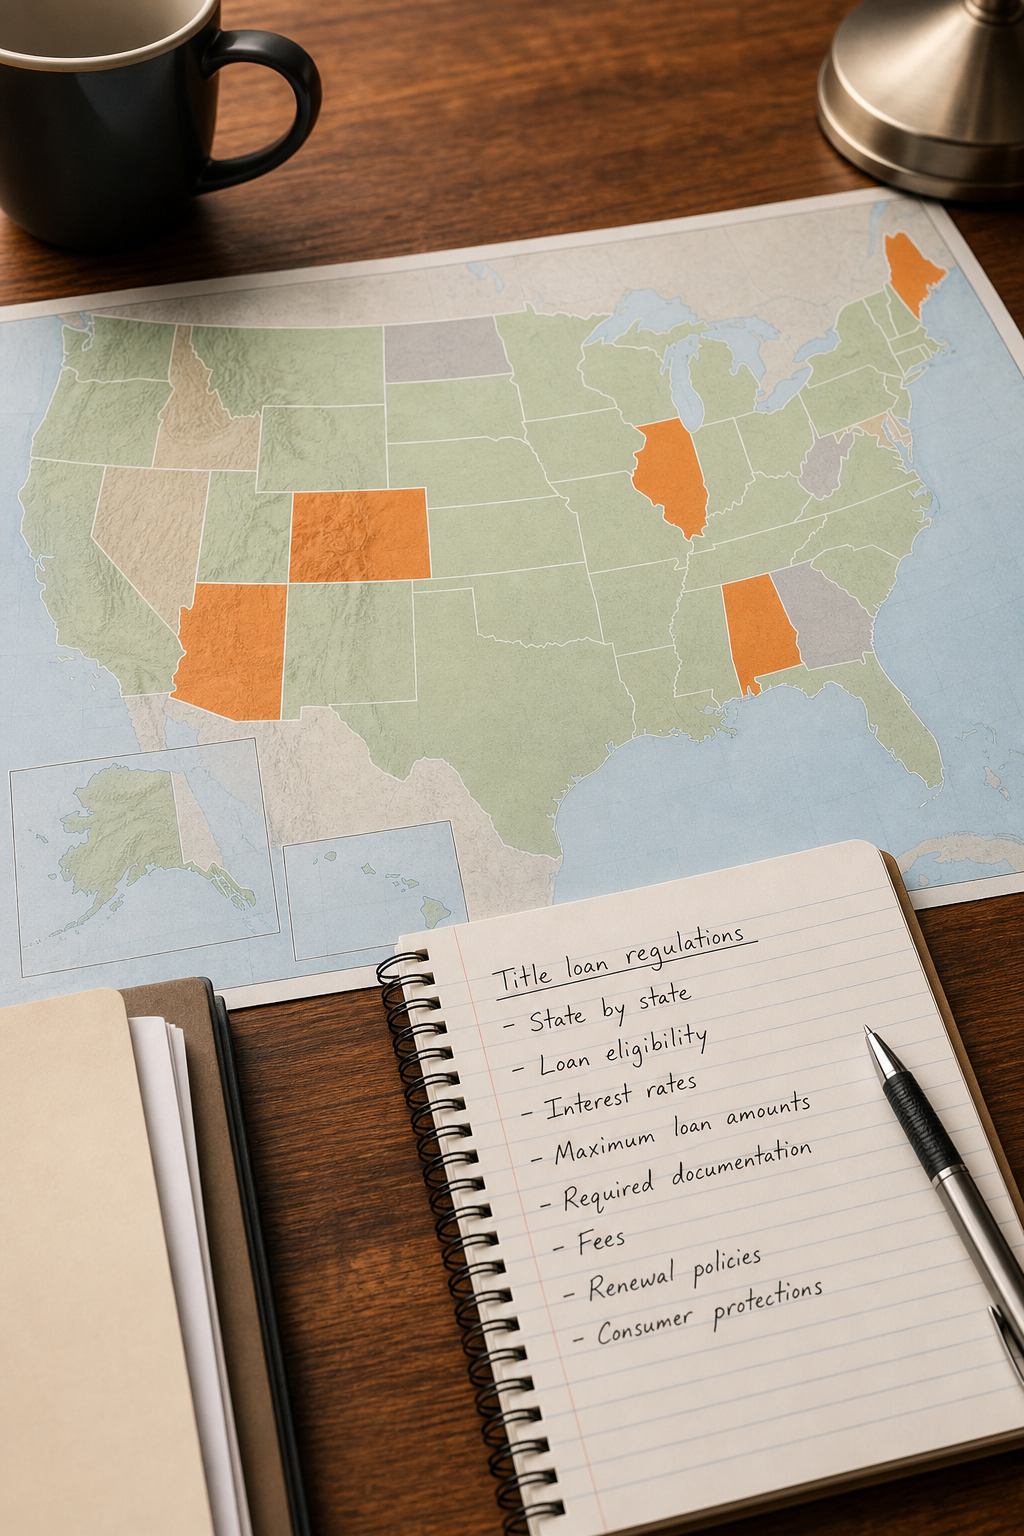
Where you live matters as much as what you own. Title loans are legal in roughly 21 of the 23 states surveyed for this guide, but the rules, rate caps, and loan limits differ sharply from one state to the next. Illinois, for example, technically caps rates at 36% APR but classifies title loans as illegal under its consumer lending framework.
Here’s a snapshot of key states and what the numbers actually look like:
The range is wide. Tennessee sits at 2% per month, which is the lowest disclosed rate in the data. Mississippi and New Hampshire both show 25% per month. Wisconsin allows loan amounts up to $25,000, while Mississippi and New Mexico cap at $2,500. Idaho, Nevada, and Utah all allow 100% loan-to-value, meaning you could theoretically borrow the full assessed value of your car.
Before you apply anywhere, confirm that title lending is legal in your state and check whether the lender holds the required state license. Your state’s financial regulator or consumer protection agency are reliable starting points for understanding what protections apply to you.
One thing the state-by-state data makes clear: no minimum credit score appears in any of the 23 entries surveyed. That’s not an oversight. It reflects how title lending actually works. The vehicle is the qualifier, not your credit file.
How EZ Car Title Loans Supports Borrowers with No Credit
EZ Car Title Loans is not a direct lender. It’s a matching platform that connects vehicle owners with state-licensed title loan lenders. That distinction matters because it means the exact APR and terms you receive depend on the lender you’re matched with and the state you’re in. EZ Car Title Loans can’t guarantee a specific rate, and it won’t.
What the platform does is remove friction. Rather than requiring borrowers to research which lenders operate in their state, EZ Car Title Loans handles that connection. Lenders on the platform evaluate vehicle equity as the primary qualification factor, not a credit score threshold. A borrower who’s been turned down by a bank because of a thin credit file or past late payments can still move through the process based on verified vehicle value.
The platform provides a range of loan amounts and APRs that vary by lender and borrower qualifications, with repayment terms that can extend from several months up to multiple years, and typically no prepayment penalties. Those figures reflect the range across lenders on the platform, not a single fixed offer. Your actual terms depend on your vehicle, your state, and the lender you’re matched with.
Applications take minutes online. Borrowers keep driving their vehicle throughout the loan term, since the lender holds a lien on the title rather than taking possession of the car. The platform supports cars, trucks, and motorcycles across multiple states.
One usable note: if your vehicle is on the higher end of the value scale, higher loan amounts may be available compared to many title lenders. If you own a late-model truck or SUV with low mileage, that equity can translate into a larger loan amount than you might expect. Managing your broader financial picture well also matters when you borrow. Resources on how umbrella insurance works can help you think through asset protection alongside any secured borrowing decision.
Disclaimer:EZ Car Title Loans is not a direct lender. APR and loan terms vary by lender and state. Defaulting on a title loan puts your vehicle at risk of repossession. This article is informational and does not constitute financial or legal advice.
Alternatives and Important Considerations
Title loans are accessible. They’re also expensive. Before you commit, it’s worth knowing what else is available and what the real risks look like.
What Else to Consider First
Personal loans for bad credit exist and are generally cheaper than title loans. Some lenders specialize in thin-credit or bad-credit borrowers and don’t require collateral. The downside is that approval may take longer and income documentation requirements are stricter. Credit unions sometimes offer secured loans using your vehicle as collateral at much lower rates than title lenders, though membership requirements and credit checks apply.
If the amount you need is small, a cash advance on an existing credit card, while not cheap, typically costs less than a high‑interest monthly title loan rate. Community assistance programs and nonprofit organizations can sometimes cover specific expenses like utilities or rent without requiring repayment at all. Local community assistance programs can connect you to resources.
The Repossession Risk Is Real
This is the part people underestimate. When a lender holds a lien on your title, they have a legal path to your vehicle if you default. Repossession can happen faster than most borrowers expect. If your car is how you get to work, losing it compounds the original financial problem immediately.
Rolling a title loan over into a new one when you can’t pay is common, but each rollover adds fees. A 30‑day loan can turn into a multi‑month cycle of debt if you’re not careful. Act early if you’re struggling to repay. Contact the lender before you miss a payment, not after.
Confirm Legality in Your State
This step is non‑negotiable. Title lending is prohibited or heavily restricted in a significant number of states. Applying through an unlicensed lender in a state that bans title loans can leave you with no legal protections. Check your state attorney general’s website or your state’s Division of Consumer Finance before you apply anywhere.
Also ask specifically about rollover policies. If you can’t pay within the original term, does the loan automatically roll over with added fees? That single question can save you from a debt spiral. Keeping good records of your financial obligations, similar to how homeowners track coverage with home warranty versus homeowners insurance comparisons, helps you stay ahead of what you owe and what you’re protected against.
FAQ
nn
Can I get a title loan with absolutely no credit history?
n
Yes. Title loans are secured by your vehicle, so lenders evaluate your car’s value and your ability to repay, not your credit file. Borrowers with no credit history at all, including people who have never used credit, qualify the same way as those with bad credit. The title must be in your name and free of liens. No minimum credit score appears in standard title loan eligibility requirements.
nn
What documents do I need to apply for a title loan?
n
You typically need a lien-free vehicle title in your name, a valid government-issued photo ID, proof of income (pay stubs, benefit letters, or bank statements), current vehicle registration, and proof of insurance. Some lenders also ask for proof of residency and personal references. Having these ready before you apply speeds up the process considerably.
nn
How much can I borrow against my car with no credit?
n
Most lenders offer between 25% and 50% of your vehicle’s current market value. On a car worth $8,000, that’s roughly $2,000 to $4,000. Some states allow up to 100% loan-to-value, like Idaho, Nevada, and Utah. State law also caps maximum loan amounts in some places, ranging from $2,500 in Mississippi to $25,000 in Wisconsin.
nn
Are title loans legal in every state?
n
No. Title loans are legal in roughly 21 of the 23 states surveyed here, but several states prohibit or heavily restrict them. Illinois, for example, classifies them as illegal despite having a rate cap on paper. Before applying, verify legality through your state attorney general’s office or state consumer finance regulator. Working only with state-licensed lenders is the safest approach.
nn
What happens if I can’t repay my title loan on time?
n
If you miss payments, the lender can repossess your vehicle. Most lenders offer the option to roll the loan over into a new one, but that adds fees and extends your debt. Contact your lender before missing a payment. Acting early gives you more options than waiting until after a default. Repossession can happen quickly once you’re in default, and losing your car often makes the original financial problem worse.
nn
Does applying for a title loan hurt my credit score?
n
In most cases, no. Most title lenders don’t run a traditional hard credit inquiry, so the application itself won’t drop your score. On the flip side, title lenders also typically don’t report your payments to the credit bureaus, so on-time payments won’t help you build credit either. A title loan is generally credit-neutral in both directions.
nn
Conclusion
nn
If you own a vehicle with a clear title, your credit score is not the barrier most people assume it is. The real eligibility questions are about your car’s value, your state’s laws, and your ability to repay. If you’re ready to explore your options, EZ Car Title Loans connects borrowers with licensed lenders who evaluate vehicle equity first, and the application takes just a few minutes online. Know your numbers, confirm your state’s rules, and borrow only what you can realistically pay back.


