

Your car’s title can put real cash in your hands fast , but the way you access that money matters a lot. APRs on title loans vary wildly, and choosing the wrong route can cost you hundreds extra or, worse, your vehicle. Here are the nine best ways to get a loan against your car title right now, plus a comparison of title loans vs. auto-equity loans, so you know exactly what you’re signing up for.
1. EZ Car Title Loans , Our Top Pick for Comparing Lenders Online
EZ Car Title Loans is an online matching platform, not a direct lender. It connects vehicle owners with licensed title loan lenders across multiple states, so you can compare offers before you commit to any single lender.
Loan amounts and APRs vary by lender and state. Repayment terms stretch from 91 days to 70 months, and no prepayment penalties apply. You keep driving your car the entire time the lender holds a lien on your title.
The application takes minutes online. You submit basic vehicle and personal details, the system routes your request to lenders that work in your state, and most applicants get a same-day decision. The platform covers cars, trucks, and motorcycles, and supports both online and in-person options depending on the lender.
What sets EZ Car Title Loans apart from simply walking into a storefront is transparency. Most competitors don’t publish their APR range publicly. If you want to explore what same-day title loan funding actually looks like across different lenders, this is where to start.
One caveat: because it’s a matching platform, the specific rate you see depends on the lender and your state. APR and terms vary. Review any lender’s full disclosure before signing.
2. Traditional Title Loan Lenders , Storefront Loans with Same-Day Funding
Physical storefront lenders are the oldest path to borrowing against your car title. You walk in, hand over your title and ID, let them appraise the vehicle, and often leave with cash the same day. No ACH transfer wait. No scanning documents at home.
These lenders typically offer 25% to 50% of your vehicle’s current market value. Repayment terms are often short , 15 to 30 days on a single-installment loan , though some offer monthly installment plans over three to six months.
The cost is the main drawback. Regulators have taken enforcement actions against car title lenders that advertised zero-percent introductory rates while charging very high APRs once the 30-day window closed. That pattern is still common. Some lenders advertise a “0% interest for the first 30 days” feature yet list APRs exceeding 300%.
If you miss a payment at a storefront lender, interest accrues daily , typically between $1 and $4 per day , and partial payments may not be accepted before your due date. One borrower shared online that after missing a single payment on a $500 loan, his total repayment climbed from $1,510 to over $1,780 due to daily interest accumulation. The lesson: keep payments on time and communicate early if you’re going to be late.
Storefronts make sense when you need cash in hand today and don’t have time to wait for an ACH transfer. Just read the full APR disclosure , not just the introductory rate , before signing.
3. Online Title Loan Lenders , Photo Inspection and Remote Document Upload
Online title lenders handle the entire process through a browser or app. You upload photos of your vehicle, your title, a government-issued ID, and proof of income. A representative appraises the car remotely based on those photos and your vehicle’s year, make, model, and mileage. If approved, funds arrive via ACH direct deposit , sometimes the same day, though next-business-day is more common.
The photo inspection usually covers the odometer, the VIN plate, all four sides of the car, and any visible damage. Park the vehicle in good light so the images are clear. Blurry or dark photos slow the process down.
Documents you’ll typically need: your lien-free title in your name, a photo ID, proof of address, and some form of income verification. Pay stubs work, but so do bank statements, Social Security award letters, or retirement benefit documentation. Some lenders also request a spare key.
Credit checks vary. Most title lenders focus primarily on your vehicle’s equity rather than your credit score. However, a reputable lender will still review your credit history as part of its risk assessment , it’s just not the deciding factor the way it is for an unsecured personal loan.
Online lending works well for borrowers who are comfortable uploading documents and don’t need cash in hand at a physical counter. The trade-off is that same-day cash , meaning actual paper bills , isn’t possible remotely. Wire transfers or direct deposit are the only funding methods.
4. Credit Union Auto-Equity Loans , Lower-Cost Alternative to Title Loans
Credit unions and some banks offer loans secured by your vehicle’s equity, but under very different terms than a traditional title lender. These are sometimes called share-secured or vehicle-equity loans, and they’re worth checking before you commit to a high-rate title loan.
The rates are the main reason to look here first. Where title lenders often charge high monthly rates, credit union secured loans typically carry single-digit to low double-digit APRs. Some federal credit unions are capped at 18% APR on most loan products. The repayment terms are also longer , two to five years is common , which lowers the monthly payment considerably.
The catch is qualification. Credit unions generally require membership, a credit check, and in some cases a minimum credit score. If your credit is thin or damaged, you may not qualify. But if you do, the savings over a title loan can be substantial. The interest cost difference between a low-APR credit union loan and a high-APR title loan rolled over monthly can be significant, making it worth exploring this option first if you are eligible.
Vehicle requirements also differ. The car usually needs to be newer, lower-mileage, and free of liens. A 2014 pickup with 180,000 miles may not qualify at a credit union but would likely pass at a title lender. Know your vehicle’s profile before you apply to either.
5. Title Loan Refinancing , Lowering Your Rate on an Existing Title Loan
If you already have a title loan with an unmanageable rate or payment, refinancing is worth pursuing. Refinancing means replacing your current title loan with a new one , either through the same lender or a different one , ideally with a lower rate, longer term, or both.
The process is similar to applying for a new title loan. You’ll need your vehicle title, proof of income, proof of address, and a photo ID. The new lender pays off your existing loan directly. In most states, the lien transfer between lenders is handled between the two companies, so you don’t have to coordinate that paperwork yourself.
Refinancing makes sense when your current monthly payment is straining your budget, or when you can qualify for better terms than you received originally , perhaps because your vehicle’s value has held up well, or because you’re applying through a platform that works with more lenders. It can also free up extra cash if the new loan amount exceeds your current payoff balance and the lender releases the surplus to you.
One thing to watch: refinancing into a longer term lowers your monthly payment, but you pay more in total interest over the life of the loan. If you can manage a slightly higher monthly payment to shorten the term, you’ll save money overall. Only refinance if the new terms are genuinely equal to or better than your current ones , not just lower monthly payments with a much longer payoff.
6. Title Loans for Military Servicemembers , Federal Protections and Rate Caps
Active-duty military servicemembers, their spouses, and dependents have a specific federal protection that doesn’t apply to most borrowers: a federal rate cap on most consumer credit products , including car title loans , at 36%.
That 36% cap includes not just the interest rate but also fees, credit insurance, and other add-ons. A title lender advertising a very high APR cannot legally charge that rate to a covered servicemember. The lender is also required to provide written and verbal disclosure of the applicable rate and the borrower’s rights before the loan is signed.
If you’re in the military and facing a financial bind that a title loan might solve, speaking with a Personal Financial Manager (PFM) on base before borrowing is widely recommended. Military relief societies offer interest-free emergency loans that may address the same need without any interest cost at all.
Servicemembers should verify that any lender they approach complies with applicable federal protections for military borrowers. A lender that charges above-cap rates to a covered borrower is violating federal law. If that happens, the loan contract may be void and the lender subject to penalties.
7. State-Licensed Title Lenders , How State Laws Affect Your Loan Terms
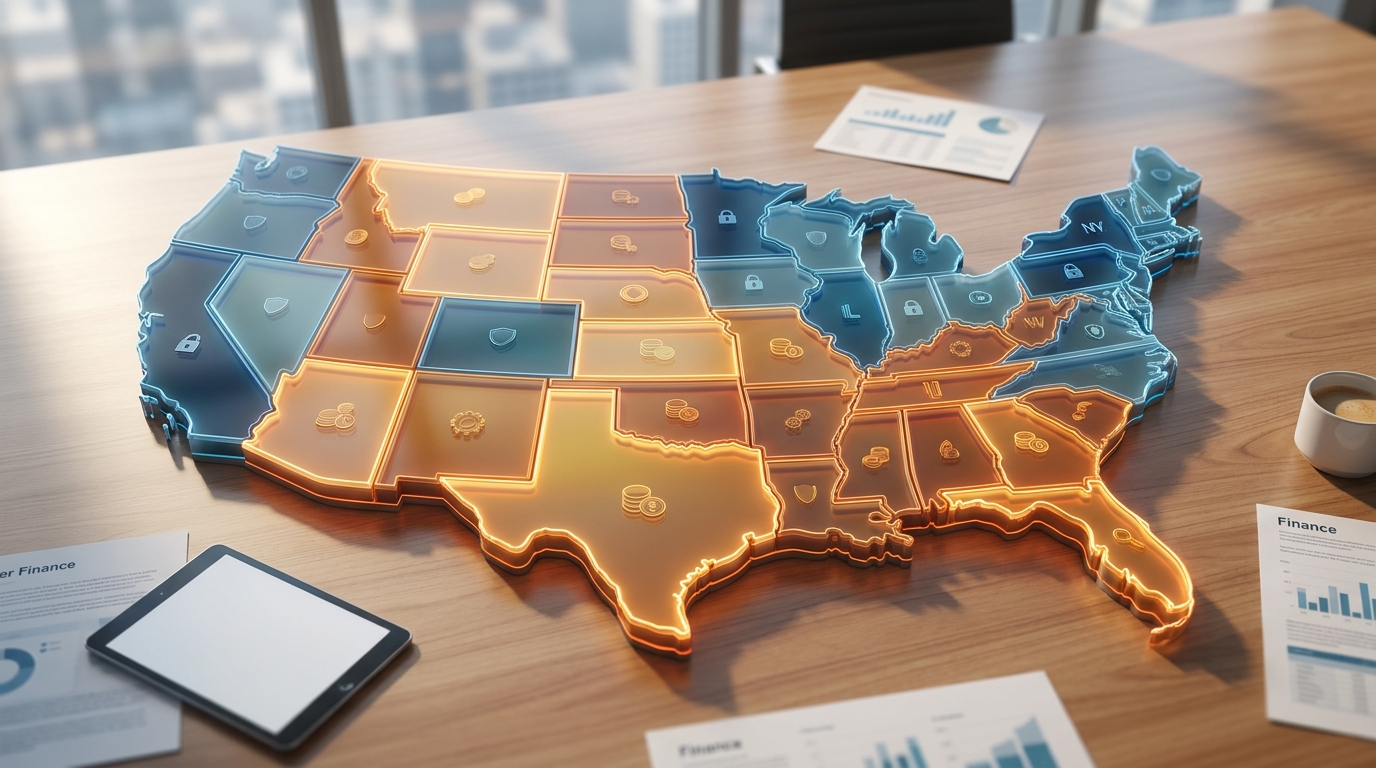
Where you live shapes your title loan more than almost anything else. The same car, the same income, and the same financial situation can produce a completely different borrowing experience depending on your state.
Title loans are currently permitted in approximately 27 states. States with dedicated title lending frameworks include Alabama, Arizona, Georgia, Idaho, Illinois, Nevada, Tennessee, Texas, Utah, and Virginia, among others. A significant number of states , including Arkansas, Connecticut, Massachusetts, Michigan, New York, North Carolina, and Pennsylvania , prohibit title loans entirely.
The rate differences between states are dramatic. In our research, the only provider advertising an APR below 36% was a Florida-based lender (Credex, at up to 35.95%). Two Georgia-based lenders openly advertised APRs exceeding 300%. Florida’s regulatory environment appears to produce meaningfully different market outcomes than Georgia’s , a operational illustration of how state law affects what you actually pay.
Some states add borrower-friendly procedural rules. Arizona requires a court order before repossession. Nevada caps monthly payments at 25% of the borrower’s pre-tax income. Tennessee requires the lender to hold the physical title during the loan period, and any loan issued by an unlicensed Tennessee lender is legally void. Alabama’s framework, by contrast, lets lenders keep all proceeds from a vehicle sale , even if the sale price exceeds what you owed.
EZ Car Title Loans operates across multiple states and connects borrowers with lenders that are licensed in their specific state. That matters because an unlicensed lender operating across state lines may not be subject to any rate cap at all. Working with a platform that screens for state licensing is one of the simplest ways to avoid that risk.
8. Selling a Car with a Title Loan , Handling an Active Lien
You can sell a car that has a title loan on it, but you can’t transfer the title until the lien is released. When you took out the loan, the lender placed a lien on your title. That lien gives them a legal claim to the vehicle. A buyer can’t receive clean ownership until the lender files a lien release , which only happens after full repayment.
Most private buyers won’t be interested in a transaction where the title can’t transfer immediately. But there are workable paths. If you’re selling to a dealership, they deal with liens regularly and will usually handle the payoff as part of the transaction. Your sale proceeds go first to retire the loan balance, and you receive whatever is left.
For a private sale, the cleanest approach is to pay off the loan first, receive the lien-free title from the lender, then sell to the private buyer with clean paperwork. If you don’t have the cash to pay off the loan independently, some buyers , especially friends or family , may be willing to structure the sale so that part of their payment goes directly to the title lender at closing, with the remainder paid to you once the lien releases.
Get the exact payoff figure from your lender before you list the car. The payoff amount may differ from the balance shown on your statement, especially if interest has accrued since the last statement date. Some lenders also charge early payoff fees, though many title lenders , including lenders in EZ Car Title Loans’ network , don’t apply prepayment penalties.
9. Filing a Complaint Against a Predatory Title Lender , CFPB and State Options
If you’ve been misled about the cost of your title loan , hidden fees, undisclosed APR, or deceptive introductory rate advertising , you have real options. Federal regulators have taken enforcement actions against title lenders specifically because companies were advertising introductory rates without disclosing the conditions a borrower had to meet to actually receive those rates, or the high finance charges that kicked in afterward.
To file a complaint, you have federal routes available through consumer protection agencies. Neither agency resolves individual disputes, but complaints create a record that helps regulators detect patterns and may trigger investigations.
At the state level, your state attorney general’s office and your state’s financial regulator both handle complaints about licensed lenders. If a lender operating in your state isn’t licensed, that itself is a violation worth reporting. In some states , like Tennessee , a loan issued by an unlicensed lender is automatically void, meaning you may owe nothing on it.
Document everything before filing: your loan agreement, payment receipts, any written or verbal statements the lender made about rates or fees, and a timeline of events. The more specific your complaint, the more useful it is to investigators.
Title Loans vs. Auto-Equity Loans , Side-by-Side Comparison
Both loan types use your vehicle as collateral, but they work differently and attract very different borrowers. Here’s a direct comparison across the factors that matter most.
Title loans are faster and more accessible to borrowers with poor credit. Auto-equity loans are significantly cheaper for borrowers who qualify. If your credit allows it, the auto-equity route is the smarter financial choice. If time is short and your credit is damaged, a title loan from a platform like EZ Car Title Loans , where APR transparency is part of the offering , is a better option than walking blind into a storefront lender advertising a teaser rate.
What to Look for Before Signing a Title Loan Agreement
Before you sign anything, the agreement must disclose the APR as a percentage and the finance charge as a dollar amount. Federal law requires this. The APR is the clearest way to compare two loans , it accounts for fees and the term length, not just the interest rate.
Check for these specifics in the contract:
- Total repayment amount: What you’ll pay back in full if you make every payment on time. Compare this to what you’re borrowing.
- Rollover policy: If you can’t pay by the due date, can you roll the loan into a new term? What does that cost?
- Prepayment penalties: Can you pay off early without extra charges? Many title lenders don’t penalize early payoff, but some do.
- Repossession procedure: How many missed payments trigger repossession? Does the lender send notice first?
- Surplus proceeds: If repossession occurs and the vehicle sells for more than you owed, do you receive the difference? Not all states require this.
Anyone planning off-road adventures or extended road trips while their vehicle is under a title loan lien should confirm the lender’s policy on vehicle use , most allow normal driving without restriction. Vehicle maintenance publications and automotive resources can help car owners get the most out of their vehicles throughout the loan period.
If something in the agreement doesn’t match what you were told verbally, ask for clarification in writing before signing. A lender that can’t or won’t explain a term clearly is a red flag worth taking seriously.
Frequently Asked Questions
Can I get a loan against my car title with bad credit?
Yes, in most cases. Title loans use your vehicle’s equity as the primary qualification factor, not your credit score. Many lenders don’t run a traditional hard credit pull. Your approval and loan amount depend mainly on what your car is worth and whether the title is in your name with no existing liens. Borrowers with past bankruptcies or missed payments have qualified through equity-based lenders.
How much can I borrow against my car title?
Most lenders offer 25% to 50% of your vehicle’s current market value. The exact amount depends on the vehicle’s year, make, model, mileage, and condition at appraisal. Loan amounts vary by lender and state; contact EZ Car Title Loans to learn what may be available for your vehicle.
What happens if I can’t repay my title loan?
If you miss payments, interest accrues daily and your lender can eventually repossess your vehicle. Most lenders send written notice before repossessing and will work with you if you reach out early. Contact your lender as soon as you know a payment is at risk , many will offer a short grace period or modified payment schedule. Do not go silent. Proactive communication almost always produces better outcomes than avoidance.
Are title loans legal in my state?
Title loans are legal in approximately 27 states. They’re prohibited in states including Arkansas, Massachusetts, Michigan, New York, North Carolina, and Pennsylvania. State laws also vary on rate caps, repossession procedures, and whether surplus vehicle-sale proceeds must be returned to the borrower. Check your state attorney general’s website or your state financial regulator for current status before applying.
Do I keep driving my car during a title loan?
Yes. With a standard title loan, the lender places a lien on your title but you retain possession and use of the vehicle throughout the repayment period. You drive it normally. Once you pay off the loan in full, the lender files a lien release and returns the title to you. The lender does not take the car unless you default.
What’s the difference between a title loan and a payday loan?
Both are short-term, high-cost loans, but they differ in collateral. A payday loan is unsecured , backed by your next paycheck. A title loan is secured by your vehicle’s title. Because title loans have collateral, lenders may offer larger amounts and slightly longer terms than payday lenders. Both carry high APRs and the risk of a debt cycle if not repaid quickly. The additional risk with a title loan is vehicle repossession on default.
The Right Starting Point
A loan against your car title can solve a real cash emergency , but the terms you accept matter enormously. Start with EZ Car Title Loans to compare multiple licensed lenders in your state before committing to any single offer. Review the full APR disclosure, check for prepayment penalties, and make sure the monthly payment fits your actual budget. If you’re ready to see what you qualify for, visit EZ Car Title Loans and get a same-day quote in minutes.


