

json
{ “Title”: ” Pros and Cons of No Credit Check Title Loans”, “MetaDescription”: “Explore the pros and cons of no credit check title loans, how they work, real APR ranges, repossession risks, and how EZ Car Title Loans can help.”, “article_html”: “
No credit check title loans sound like an easy fix when your credit score is low and you need cash fast. But the “no credit check” part doesn’t mean the loan is cheap or risk-free. Before you hand over your car title, here’s what you actually need to know.
nn
What Is a No Credit Check Title Loan?
A no credit check title loan is a short-term, secured loan that uses your vehicle as collateral. Instead of pulling your credit history to decide whether you qualify, the lender looks at your car’s value. You hand over the title, they give you cash, and you keep driving while you repay.
The “no credit check” label is mostly accurate. Most title lenders skip the hard inquiry that banks run. Some do a soft pull to verify your identity, but that typically won’t affect your credit score. What matters to the lender is whether your car is worth enough to cover the loan if you default.
These loans are legal in roughly 27 states, according to Experian’s overview of car title loans. Other states ban them outright or have strict rate caps that limit how lenders can structure them. So eligibility depends heavily on where you live.
The loan amount is usually 25% to 50% of your vehicle’s market value. Depending on the car’s value, borrowers may qualify for a loan representing a portion of that equity. Repayment terms are short. Many title loans are due in 30 days, though some lenders offer installment plans running three to six months.
Here’s the part most ads skip: the cost. APRs on no-credit-check title loans typically run well above 100%. Auto title loans often carry APRs around 170%. Other sources place typical APRs at 300% or higher. Compare that to a credit union title loan, which can sit at 2% to 3% interest, but those require a credit score of roughly 700 or better. The no-credit-check option is the expensive tier, not the budget one.
Disclaimer: EZ Car Title Loans is not a direct lender and cannot guarantee specific APRs or terms. Rates, fees, and repayment conditions vary by lender and state. Failure to repay may result in vehicle repossession.
How No Credit Check Title Loans Work: Process and Eligibility
nn nn
The process is faster than a bank loan. Most lenders can approve you the same day you apply, sometimes within hours. Here’s how it generally works.
nn
First, you need to own your vehicle outright. The title must be lien-free, meaning no other lender has a claim on it. The name on the title must match your government-issued ID exactly. If you still owe money on your car loan, you likely won’t qualify with most lenders.
nn
Once you apply, the lender appraises your vehicle. Some do this in person at a store location. Others work remotely, using photos you submit online. The appraisal determines how much you can borrow. A well-maintained car in good condition typically gets a higher offer than one with high mileage or visible damage.
nn
You’ll also need to show proof of income and a valid ID. Some lenders ask for proof of residence. Employment isn’t always required. Lenders may accept Social Security income, disability payments, or other regular income sources as proof you can repay.
nn
After approval, you transfer the title to the lender. They hold it while you repay. You keep your car and keep driving it throughout the loan term. Once you pay off the balance in full, the lender releases the title back to you.
nn
Funds typically arrive by direct deposit, check, or sometimes a prepaid card. Same-day cash is common. That speed is one of the main reasons people choose these loans over traditional bank products that can take days or weeks to fund.
nn
One thing to check before you apply: make sure the lender is licensed in your state. Title lending rules vary widely. A licensed, regulated lender is a non-negotiable baseline, because unlicensed lenders operate outside the consumer protections your state provides.
nn
Pros of No Credit Check Title Loans
These loans aren’t popular by accident. They solve a real problem for a specific group of borrowers. Here’s where they genuinely help.
Access when traditional lenders say no
If your credit score is low, recovering from bankruptcy, or simply thin, most banks and credit unions will turn you down for an unsecured loan. A title loan sidesteps that barrier entirely. The lender’s decision rests on your car’s equity, not your credit file. That makes it one of the few doors still open to borrowers with damaged credit histories.
Fast approval and same-day cash
Banks can take days or weeks to process a loan application. Title loans move much faster. Approval can happen within hours, and funds often arrive the same day. For someone facing an emergency, an overdue bill, or a medical expense that can’t wait, that speed matters. The timeline from application to cash in hand is shorter than almost any other secured lending product.
You keep driving your car
A common misconception is that you have to surrender your vehicle to get a title loan. You don’t. The lender holds the title document, not your keys. You keep driving throughout the entire loan term. That’s important because losing access to your car would make it harder to work and repay the loan in the first place.
Loan amounts tied to vehicle value, not income
Title loans can offer higher amounts than payday loans, which are capped at a few hundred dollars in most states. Because the loan is based on your vehicle’s market value, borrowers with newer or higher-value cars can access more cash. Loan amounts are typically a percentage of the vehicle’s equity and vary by lender and state regulations.
Minimal paperwork
The application is straightforward. You typically need your title, a government-issued ID, proof of income, and proof of residence. No tax returns. No employment verification letters. No lengthy credit review. For borrowers who’ve been buried in bank paperwork before, the simplicity is a real advantage.
If you’re weighing this option against other short-term products, it helps to understand the comparison. The differences between car title loans and payday loans are significant, especially when it comes to loan amounts and repayment terms.
Cons and Risks of No Credit Check Title Loans
The advantages above are real. So are the downsides, and they’re serious enough that you need to understand them before you sign anything.
High APRs that can trap you in debt
This is the biggest problem. Title loans carry APRs that most borrowers don’t fully grasp when they see the monthly fee. A lender charging 25% per month sounds manageable. But 25% monthly equals roughly 300% APR. If you borrow $1,000 and can’t pay it off in 30 days, you roll it over and owe another $250 in fees. Two months in, you’ve paid $500 in fees on a $1,000 loan.
The cycle of rolling over a loan is how many borrowers end up in worse shape than when they started. Each rollover adds fees. The balance grows. The car stays at risk longer.
Vehicle repossession is a real outcome
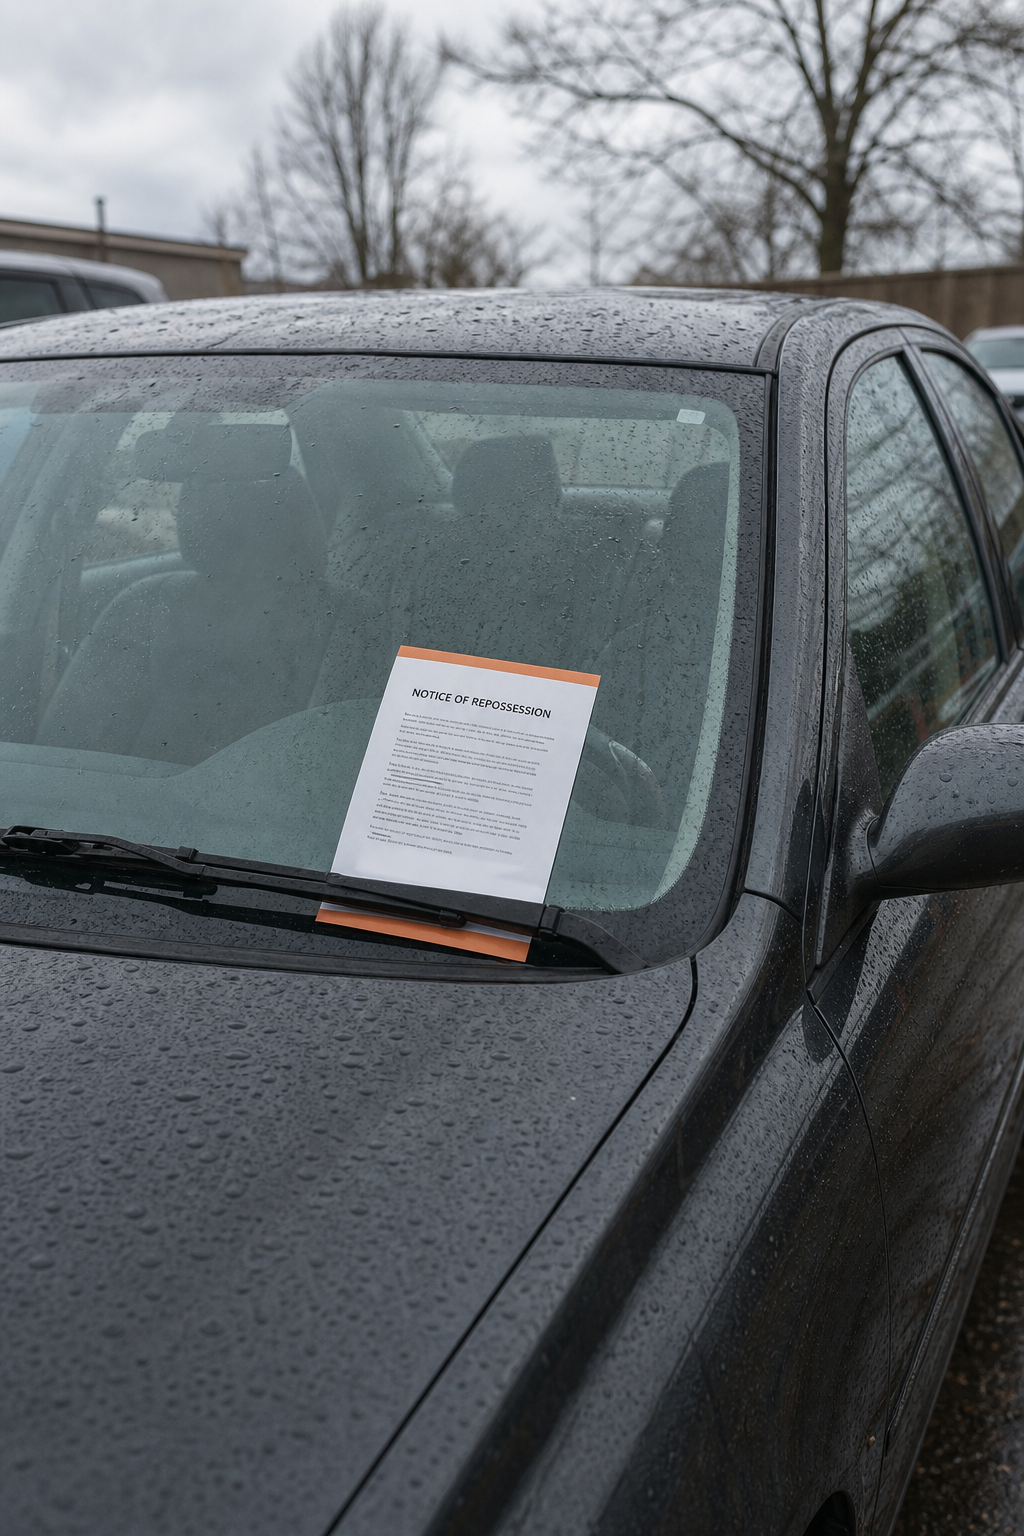
If you default, the lender can repossess your car. This isn’t a theoretical risk. Regulators describe repossession as a common outcome when borrowers can’t repay. Losing your car can cost you your job, your ability to handle family responsibilities, and your financial stability. The loan that was supposed to solve an emergency becomes the emergency.
In most states, lenders must notify you before repossessing. If you get that notice, act early. Contact the lender immediately and ask about restructuring the loan. Waiting makes it worse.
Short repayment windows
Most title loans are due in 15 to 30 days. Some installment options stretch to three to six months. Either way, the repayment window is short compared to a personal loan from a bank, which might give you two to five years. If your financial situation doesn’t improve quickly, a short term can make repayment nearly impossible without rolling over.
No credit-building benefit
Most title lenders don’t report your payments to the credit bureaus. That means paying on time won’t improve your credit score. You’re paying a high APR for a loan that leaves your credit exactly where it was. If you default and the lender repossesses and sells the car, that can show up on your credit report and cause real damage.
Limited state availability
Title loans are banned or heavily restricted in about half of US states. If you live in a state where they’re not permitted, you won’t have access to them at all. And in states that allow them, rate caps and terms vary widely, so the product you get in one state may look very different from what’s available in another.
Managing your finances around a title loan requires careful budgeting. People who are already paying close attention to their household expenses, like tracking renters insurance or understanding what renters insurance covers, tend to be better positioned to handle the short repayment windows these loans demand.
EZ Car Title Loans: How We Help You Find the Right No Credit Check Title Loan
nn
EZ Car Title Loans is not a direct lender. It’s a loan-matching platform that connects borrowers with a network of licensed title loan lenders across multiple states. That distinction matters.
nn
When you apply through EZ Car Title Loans, your application goes to multiple lenders rather than just one. The platform returns the offer that fits your situation. That means you’re not locked into a single lender’s rate. You see competing options, which gives you more room to find terms that work for your budget.
nn
The platform is upfront about how it works. APRs and loan amounts vary by lender and state. EZ Car Title Loans doesn’t promise a specific rate or guarantee approval, because it can’t. What it does is make the process faster and more transparent than walking into a single storefront and accepting whatever terms you’re handed.
nn
Qualification focuses on your vehicle’s equity. A low credit score, past bankruptcy, or no credit history won’t automatically end your application. The lender evaluates your car’s value and your ability to repay. You keep driving your vehicle throughout the loan term.
nn
Same-day approval is available for qualified borrowers. Funding typically arrives within 24 hours of approval via direct deposit. The application takes minutes online.
nn
One honest caveat: because EZ Car Title Loans works with third-party lenders, your final rate depends on which licensed partner operates in your state and what your vehicle is worth. Read the loan agreement carefully before signing. Understand the APR, the repayment schedule, and what happens if you miss a payment. Avoid surprises by asking every question before you commit.
nn
If you’re not sure whether a title loan is the right fit, EZ Car Title Loans also provides resources to help you compare options. The goal is to make sure you understand what you’re getting into, not just to get you approved fast.
nn
Frequently Asked Questions
Can I really get a title loan with no credit check?
Yes, most title lenders skip the traditional credit check because your vehicle secures the loan. They focus on your car’s value and your ability to repay. Some lenders do a soft pull to verify your identity, but that typically won’t affect your credit score. Always ask the lender directly whether they run a hard inquiry before you apply.
What happens if I can’t repay my title loan?
If you default, the lender can repossess your vehicle. Most states require the lender to notify you first. If you’re struggling to repay, contact the lender immediately. Options may include extending the loan term, setting up a payment plan, or refinancing with a lower-cost loan. Acting early gives you more options than waiting until repossession begins.
How much can I borrow with a no credit check title loan?
Most lenders offer a loan amount equal to a portion of your vehicle’s current market value, often between about a quarter and half of that value. The exact amount depends on the lender and your state’s regulations. The lender determines your car’s value through an appraisal, which considers the make, model, year, mileage, and condition.
Do title loans affect my credit score?
Usually not in either direction. Most title lenders don’t report on-time payments to the credit bureaus, so paying perfectly won’t build your credit. A repossession, however, can appear on your report and cause significant damage. If building credit is a goal, a title loan isn’t the right tool for that.
Are no credit check title loans legal in my state?
Title loans are legal in roughly 27 states. Other states ban them outright or restrict them heavily through rate caps or licensing requirements. Before applying, confirm that the lender is licensed and operating legally in your state. Your state attorney general’s office or state regulator can verify a lender’s licensing status.
What’s the difference between a title loan and a payday loan?
A title loan is secured by your vehicle, which lets you borrow more than a payday loan and sometimes at a lower rate. Payday loans are unsecured and typically capped at a few hundred dollars. Both carry high APRs and short repayment windows. The key difference is that a title loan puts your car at risk, while a payday loan doesn’t involve collateral.
Conclusion
nn
A no credit check title loan can get cash in your hands fast when other options are closed. But the APR is high, the repayment window is short, and your car is on the line if things go wrong. If you’ve weighed the risks and a title loan still makes sense for your situation, start with a platform that shows you multiple lender offers and gives you the full terms before you sign. EZ Car Title Loans connects you with licensed lenders across multiple states and is transparent about how the process works. Apply online in minutes and keep driving while you repay.


