

json
{ “Title”: ” Requirements for Same Day Car Title Loan Explained”, “MetaDescription”: “Learn the exact requirements for a same day car title loan: eligibility, documents, state laws, and typical costs to help you decide quickly.”, “article_html”: “
Most people assume a same day car title loan comes with a long, complicated list of rules. It doesn’t. The core checklist is short, and if you own your vehicle free and clear, you’re likely closer to qualifying than you think. Here’s what you actually need to know before you apply.
nn
Understanding Same Day Car Title Loans
A car title loan is a short-term secured loan. You hand the lender a lien on your vehicle’s title, and in return you get cash, usually within the same day. You keep driving your car throughout the loan term. Once you pay off the balance, the lender releases the lien and you get your title back.
The loan amount is tied to your car’s value, not your credit score. Most lenders offer somewhere between 25% and 50% of what the vehicle is worth. So if your car appraises at $6,000, you might qualify for a loan amount based on a percentage of its value, varying by lender and state.
Speed is the main draw. In-store applications can move from paperwork to cash in as little as 30 minutes. Online applications typically fund the next business day via direct deposit, though same-day funding is possible at some lenders if you apply early.
One thing to understand upfront: EZ Car Title Loans is not a direct lender. It connects borrowers with a network of licensed lending partners across multiple states. That matters because APR, loan amounts, and exact terms vary by lender and by where you live. The baseline requirements, though, are consistent enough that a clear picture is possible.
Lenders are required to disclose the finance charge and APR in writing before the loan agreement is signed. Read those numbers carefully before you commit.
Key Eligibility Criteria
nn
The eligibility bar for a same day car title loan is lower than most people expect. There’s no minimum credit score in most cases, and lenders rarely run a hard credit check. What they do check is whether you own your vehicle outright and whether you can reasonably repay the loan.
nn
Age and Ownership
n
You must be at least 18 years old. Every state that permits title lending sets this as the floor, tied to the legal age for entering a contract. Beyond that, the vehicle must be titled in your name with no active liens. If you still owe money on an auto loan, most lenders won’t accept the title until that balance is paid off.
nn
Here’s something that surprises a lot of borrowers: no state in a recent review of 19 state-level data points listed a minimum vehicle age requirement. Older cars and newer cars are both eligible, as long as the vehicle has enough market value to secure the loan amount you’re requesting.
nn
Income Verification
n
You don’t need a traditional job, but you do need some form of regular income. Lenders want to know the loan is repayable. Accepted sources typically include pay stubs, Social Security or disability benefit letters, retirement income, bank statements showing regular deposits, and self-employment records. The specific documents vary by lender.
nn
Credit Score
n
Credit requirements are rarely disclosed publicly. Texas-based lenders explicitly operate without a credit check in many cases, and a second category of lenders simply notes that no perfect credit is required without specifying a minimum score. The remaining majority of states provide no credit-score data at all, which suggests many lenders set no formal threshold. EZ Car Title Loans works with lenders that focus on vehicle equity as the primary qualification factor, making past credit problems much less of a barrier than with personal loans.
nn
If you’re exploring your options across loan types, understanding how a title loan compares to other secured borrowing can help you weigh the trade-offs. The EZ Car Title Loans guide on title loans with bad credit walks through exactly what lenders look at when credit history isn’t the deciding factor.
nn
Vehicle Condition
n
The car doesn’t need to be in perfect shape, but it does need to be operational and roadworthy. Minor cosmetic issues won’t disqualify you. Major mechanical problems or safety issues can affect the appraised value, which in turn affects how much you can borrow.
nn
Document Checklist for Same Day Approval
Getting your documents together before you apply is the single fastest way to speed up same-day funding. The list is short. Most of it is probably already in your glove box or a kitchen drawer.
The Core Documents
- Lien-free vehicle title in your name, This is the most important document. The name on the title must match your government-issued ID exactly. If there’s a spelling discrepancy or a name change, resolve it or bring supporting documentation before you apply.
- Government-issued photo ID, A driver’s license, state ID, military ID, or valid passport all work. It must be current and not expired.
- Proof of income, Pay stubs, bank statements, benefit award letters, or tax returns depending on your income source. Self-employed applicants typically need bank statements or profit-and-loss records.
- Current vehicle registration, Must be in your name and up to date.
- Proof of residence, A utility bill, lease agreement, or mortgage statement with your current address.
- Vehicle insurance, Most lenders require at least minimum liability coverage. Requirements vary by state.
Documents That May Also Be Required
- A spare set of vehicle keys (some lenders request this)
- References (personal or professional contacts)
- Bank account information for loan disbursement
- Social Security documentation in some states
State regulatory agencies note that car title lenders must be registered with the appropriate state financial regulator, and that getting a loan from an unregistered lender can be costly and risky. Before you hand over any documents, confirm the lender is licensed in your state.
If Your Title Is Electronic
Many states now use Electronic Lien and Title (ELT) systems, meaning there’s no paper title to hand over. That’s fine. The lender verifies ownership and places a lien digitally. You’ll still need your registration, ID, proof of income, and insurance. The format of the title doesn’t change the loan amount or approval criteria.
State‑by‑State Legal Requirements
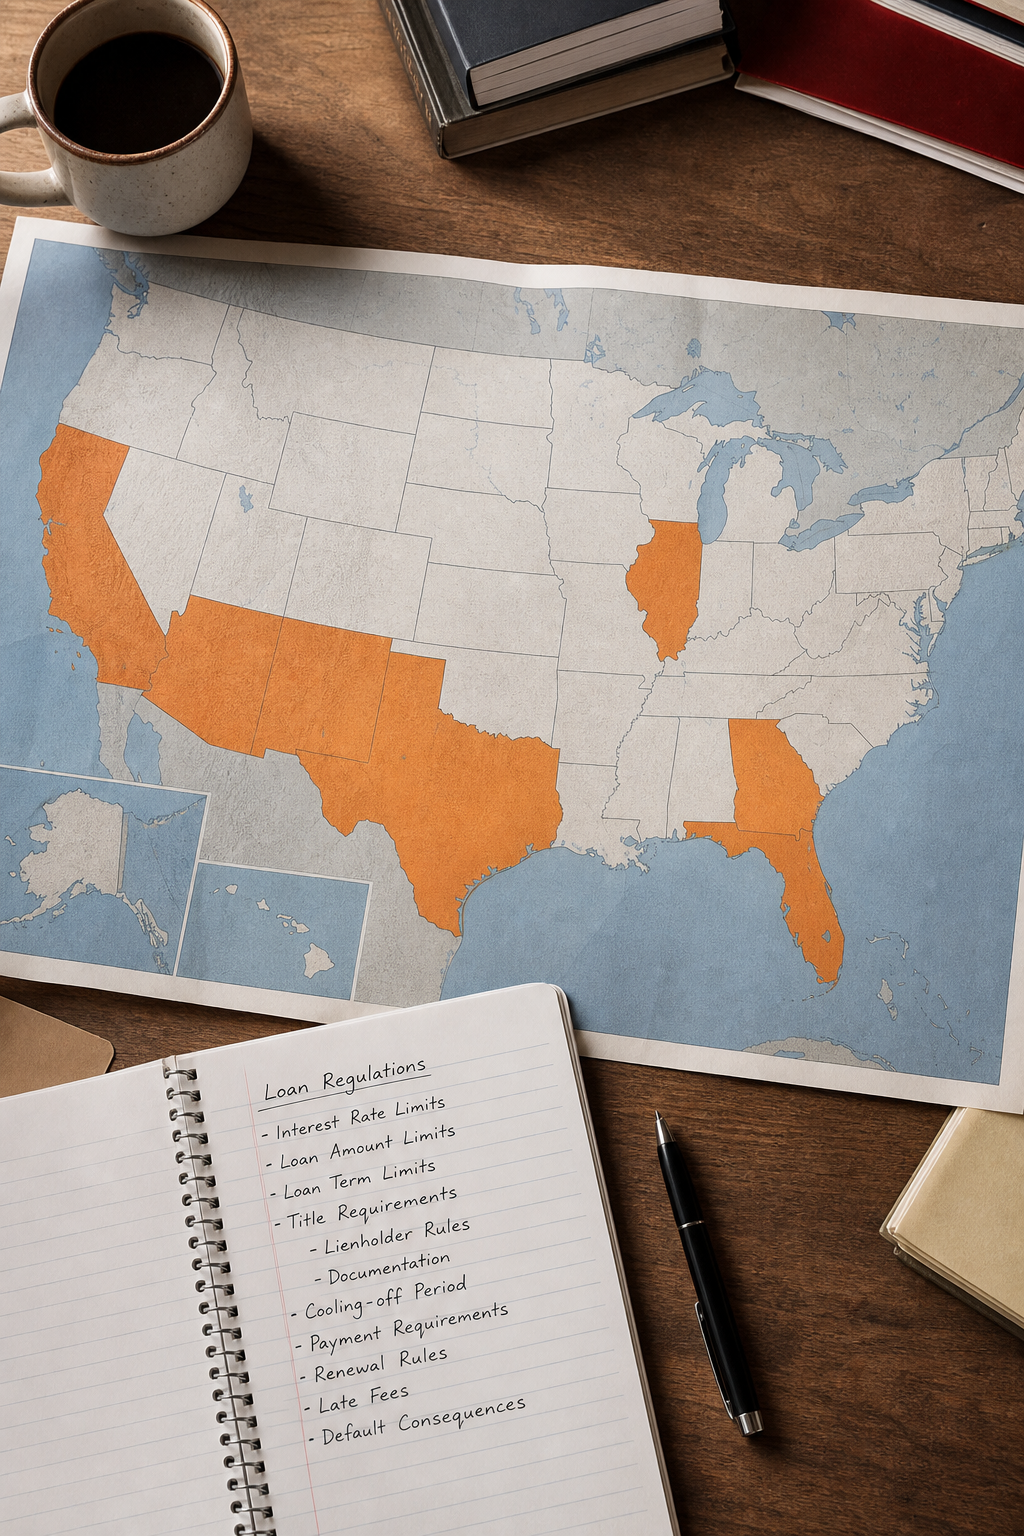
Where you live shapes your title loan options more than almost any other factor. Title loans are currently legal in approximately 27 states. Several others prohibit them outright, including Alaska, Arkansas, Connecticut, Massachusetts, Michigan, New Jersey, New York, North Carolina, and Pennsylvania, among others. If you live in a prohibited state, no licensed lender can offer you a title loan regardless of your vehicle’s value.
Why Rules Vary So Much
The federal government sets very few direct rules for the title loan industry. That means states handle their own regulation, and they’ve taken dramatically different approaches. Some have dedicated title lending statutes with rate caps and term limits. Others regulate title loans under broader pawnbroker or consumer lending laws. A few permit them through legal workarounds that weren’t originally designed for the product.
Virginia: A Clear Case Study
Virginia is the one state in publicly available data with a concrete loan-to-value cap: lenders cannot advance more than 50% of the vehicle’s appraised value, and loan terms are capped at 12 months. Virginia also requires lenders to be licensed by the Virginia State Corporation Commission. That licensing requirement is notable because it doesn’t appear in the publicly available data for most other states, which doesn’t mean those states don’t have licensing rules , it means the information isn’t always easy to find.
Texas
Texas operates through a distinctive structure. Lenders register as credit access entities and broker loans between borrowers and third‑party lenders. In major Texas cities like Dallas, Houston, San Antonio, and Austin, local regulations cap loan amounts at 70% of the vehicle’s market value or 3% of the borrower’s annual income, whichever is lower. Loan terms cannot exceed 180 days in those cities. If you’re in Texas, understanding the state’s specific framework matters before you apply.
Arizona and Nevada
Arizona uses a sliding interest rate scale tied to loan size. Loans up to $500 carry a monthly rate of 17%, with rates declining as the loan amount rises. Borrowers have one business day to cancel without penalty. Nevada requires lenders to verify borrower income and limits monthly payments to 25% of the borrower’s pre‑tax monthly income. Both states offer more borrower protections than many others.
What This Means for You
EZ Car Title Loans operates across multiple states and connects borrowers with lenders who are licensed where you live. That matters because a lender licensed in one state may not be authorized to operate in yours. Always confirm licensing before submitting personal information. Your state’s financial regulatory agency website typically has a license lookup tool.
Protecting your property while you manage financial obligations matters too. If you own a home in California, for example, understanding your coverage options, like those reviewed in this guide to homeowners insurance in Los Angeles, is a separate but equally important part of managing financial risk.
Typical Loan Terms and Costs
Understanding what a car title loan actually costs is just as important as knowing whether you qualify. The numbers can be surprising if you’re used to traditional lending.
The APR on a title loan looks very different from a personal loan or credit card. A monthly finance fee can translate to a very high annualized rate. If you borrow $1,000 and can’t repay in 30 days, rolling the loan over adds another fee on top of the original balance. That cycle can accelerate debt quickly.
EZ Car Title Loans works with lenders whose repayment terms run from 91 days up to 70 months for qualifying borrowers, with no prepayment penalties. Longer terms reduce the monthly payment pressure compared to a 30-day balloon structure. That’s worth asking about specifically when you review any loan offer.
The Repossession Risk
This is the part most borrowers don’t think about until it’s too late. If you default, the lender has the legal right to repossess your vehicle. In some states, lenders can keep all proceeds from the sale even if it exceeds what you owe. In others, they must return the surplus to you. Know your state’s rules before you sign.
If you’re struggling to make a payment, act early. Contact the lender before the due date. Some will work with you on an extension. Each extension typically carries a fee, but it’s less costly than repossession and the loss of your vehicle.
The Military Lending Act provides an important protection worth knowing: active-duty service members and their dependents are capped at a 36% Military Annual Percentage Rate (MAPR) on car title loans. If you’re in the military, that cap applies regardless of what the lender’s standard rate would otherwise be.
FAQ
What do I need to qualify for a same day car title loan?
You need a lien-free vehicle title in your name, a government-issued photo ID, proof of income, current vehicle registration, and proof of residence. Most lenders also require active vehicle insurance. You must be at least 18 years old. Credit score is rarely a formal requirement since the loan is secured by your vehicle’s value.
Does my car have to be a certain age to qualify?
No minimum vehicle age is publicly listed in most states. What matters is the vehicle’s current market value, not how old it is. An older car with low mileage and good condition can still qualify. The lender appraises the vehicle and bases the loan amount on that appraised value, typically 25% to 50% of what the car is worth.
Can I get a same day title loan with bad credit?
Yes, in most cases. Title loans are secured by your car’s equity, so many lenders don’t run a traditional credit check. EZ Car Title Loans connects borrowers with lenders that use vehicle value as the primary qualification factor. Past missed payments, a prior bankruptcy, or collections don’t automatically disqualify you from consideration.
Are car title loans legal in every state?
No. Title loans are legal in approximately 27 states. States like New York, Pennsylvania, Massachusetts, and New Jersey prohibit them entirely. If you live in a state where they’re banned, no licensed lender can offer you one. Check your state’s financial regulatory agency website to confirm current rules before applying.
What happens if I can’t repay my title loan on time?
Contact your lender before the due date. Some lenders offer extensions, though each one adds fees to what you owe. If you default without making arrangements, the lender can repossess your vehicle. In some states, lenders can keep all sale proceeds even if the sale price exceeds your balance. Act early to avoid that outcome.
How much can I borrow against my car title?
Most lenders offer 25% to 50% of your vehicle’s appraised market value. Loan amounts also depend on your state’s rules; for example, some states cap loans at 50% of vehicle value. EZ Car Title Loans works with lenders that can accommodate higher-value vehicles.
Conclusion
nn
The requirements for a same day car title loan are shorter than most people expect: a lien-free title in your name, a photo ID, proof of income, current registration, and insurance. Your credit score rarely blocks you. What matters most is your vehicle’s value and which state you’re in. If you’re ready to see what you qualify for, EZ Car Title Loans can match you with licensed lenders in your state. For a deeper look at how the process works in a specific state, the complete guide to car title loans in Texas is a good starting point for understanding how state rules shape your options.


