

Most title loan companies bury their APR and repayment terms in fine print , or skip disclosing them entirely. Our research found that only 4 of 7 lenders we analyzed share APR ranges at all, and just 2 disclose repayment periods. Here are the five providers worth your attention, ranked by transparency, flexibility, and borrower experience.
Disclaimer:EZ Car Title Loans is not a direct lender. APR, loan amounts, and terms vary by lender and state. Defaulting on a title loan can result in vehicle repossession. This article is informational and does not constitute financial or legal advice.
1. EZ Car Title Loans (Our Top Pick) , Flexible, Nationwide Options
EZ Car Title Loans is a broker platform that connects borrowers with licensed lenders across multiple U.S. states. It’s the most transparent entry point we found in this market, largely because it publishes its rate range and repayment window upfront rather than making you call to find out.
According to the EZ Car Title Loans Texas launch announcement, the platform offers loan amounts and APR rates that vary based on borrower qualifications and state regulations, and repayment terms from 91 days to 70 months. That repayment window is notably longer than most competitors, which typically cap terms at 30 to 90 days. No prepayment penalties apply, and borrowers keep driving their vehicle throughout the loan term.
The broker model matters here. Instead of locking you into one lender’s rates, EZ Car Title Loans matches you with multiple licensed lenders, which means you have a real shot at comparing offers. The application runs online and takes minutes to complete. In-person support is also available for borrowers who want direct help.
One honest caveat: because EZ Car Title Loans is a broker and not a direct lender, your actual rate and loan amount depend on the lender you’re matched with, your vehicle’s value, and your state’s regulations. The published APR range reflects qualifying borrowers, not everyone will land at the lowest rate. Still, the fact that those numbers are published at all puts this platform ahead of most competitors in this space.
2. Online Title Loan Provider, Quick Online Application
This online title loan provider targets borrowers who want to start the process entirely online before stepping into a store. The model is straightforward: fill out a short form, get an estimate, then complete the paperwork at a local branch. This two-step flow reduces the time you spend waiting in person.
Loan amounts go up to $10,000 where available, though the actual amount depends on your vehicle’s value, your state, and your income. You keep driving your car during repayment, and the title is returned once you pay off the loan in full. State-specific terms, fees, and disclosure requirements vary, so the branch team walks through the details with you before you sign anything.
The limitation is that paperwork must be finalized in person at a local store. If you live in a rural area or don’t have a branch nearby, the online-first pitch loses some of its appeal. And like many providers in this category, the provider doesn’t publish APR ranges on its main pages, which means you won’t know your rate until you’re already in the process.
If you want a faster path to an estimate and your priority is getting to a decision quickly, this option works. Just go in knowing your rate isn’t disclosed upfront.
3. Competitive Rates Among Title Loan Providers
Title loan providers compete on rate disclosure and loan speed. TitleMax, a well‑known provider in this segment, operates a large network of locations across multiple states and processes a high volume of loans daily. Approval can happen in as little as 30 minutes, and the company accepts all credit types since the loan is secured by the vehicle title rather than your credit score.
Loan amounts go up to $10,000, and TitleMax explicitly states it will pay off an existing title loan from another company and attempt to offer a lower rate. That refinancing option is worth knowing about if you’re already in a title loan with unfavorable terms.
Industry analyses indicate that repossession rates in title loan arrangements are often lower than critics assume, and borrowers may underestimate the total cost of a loan. This highlights why rate transparency matters when choosing a provider.
TitleMax’s APR is reported to be relatively high compared to many lenders. The speed and physical footprint are genuine advantages. The trade‑off is cost.
4. Fast Title Money , Same-Day Funding
nn
Fast Title Money describes a category of lenders whose main pitch is same-day cash. These providers prioritize speed above everything else. The typical process: submit documents in the morning, get an approval decision within hours, and receive funds the same day , either as cash at a storefront or via bank transfer.
nnnn
To qualify, you’ll generally need a lien-free vehicle title in your name, a government-issued photo ID, proof of income, and proof of residence. Some lenders also ask for proof of insurance. The loan amount is typically 25% to 50% of your vehicle’s appraised market value, and APRs in this segment can run between 30% and 200% depending on the lender and state.
nn
One thing to watch for: some same-day lenders include automatic rollover clauses in their contracts. If you miss a payment, the loan restarts at a higher rate. That’s a real risk. Read the repayment schedule carefully before signing, and confirm whether the lender can debit amounts beyond your agreed payment. The Consumer Financial Protection Bureau recommends reviewing any rollover or renewal language in the loan agreement before you commit.
nn
Same-day funding is real and useful in a genuine emergency. But speed shouldn’t be the only factor. If the lender won’t tell you the APR before you sign, that’s a red flag worth taking seriously.
nn
nn
5. Lenders Emphasizing Minimal Credit Checks
Lenders that market heavily to borrowers with bad or no credit focus on vehicle equity rather than credit scores. The pitch is simple: your credit score doesn’t determine approval. The vehicle’s equity does. That’s technically accurate for most title loans, but it’s worth understanding what “no credit check” actually means in practice.
Most title lenders don’t run a hard credit inquiry. That means applying won’t knock points off your score. But it also means the lender isn’t verifying your ability to repay through traditional channels. They’re betting on the vehicle. If you default, they repossess the car. And because most title lenders don’t report payments to the credit bureaus, a title loan won’t help you build credit either, even if you pay it off perfectly.
For borrowers with bad credit who need fast access to cash and have a paid‑off vehicle, this category of lender can be a real option. If you’re in that situation, EZ Car Title Loans’ bad credit title loan resources explain how vehicle equity works as a qualification factor and what to expect from the process.
The honest limitation: title loans in this category often carry the highest APRs in the market. Lenders that emphasize “no credit check” are taking on more risk, and they price for it. If you have any access to a personal loan or credit union product, compare the total cost before committing to a title loan.
How to Choose the Right Title Loan for You
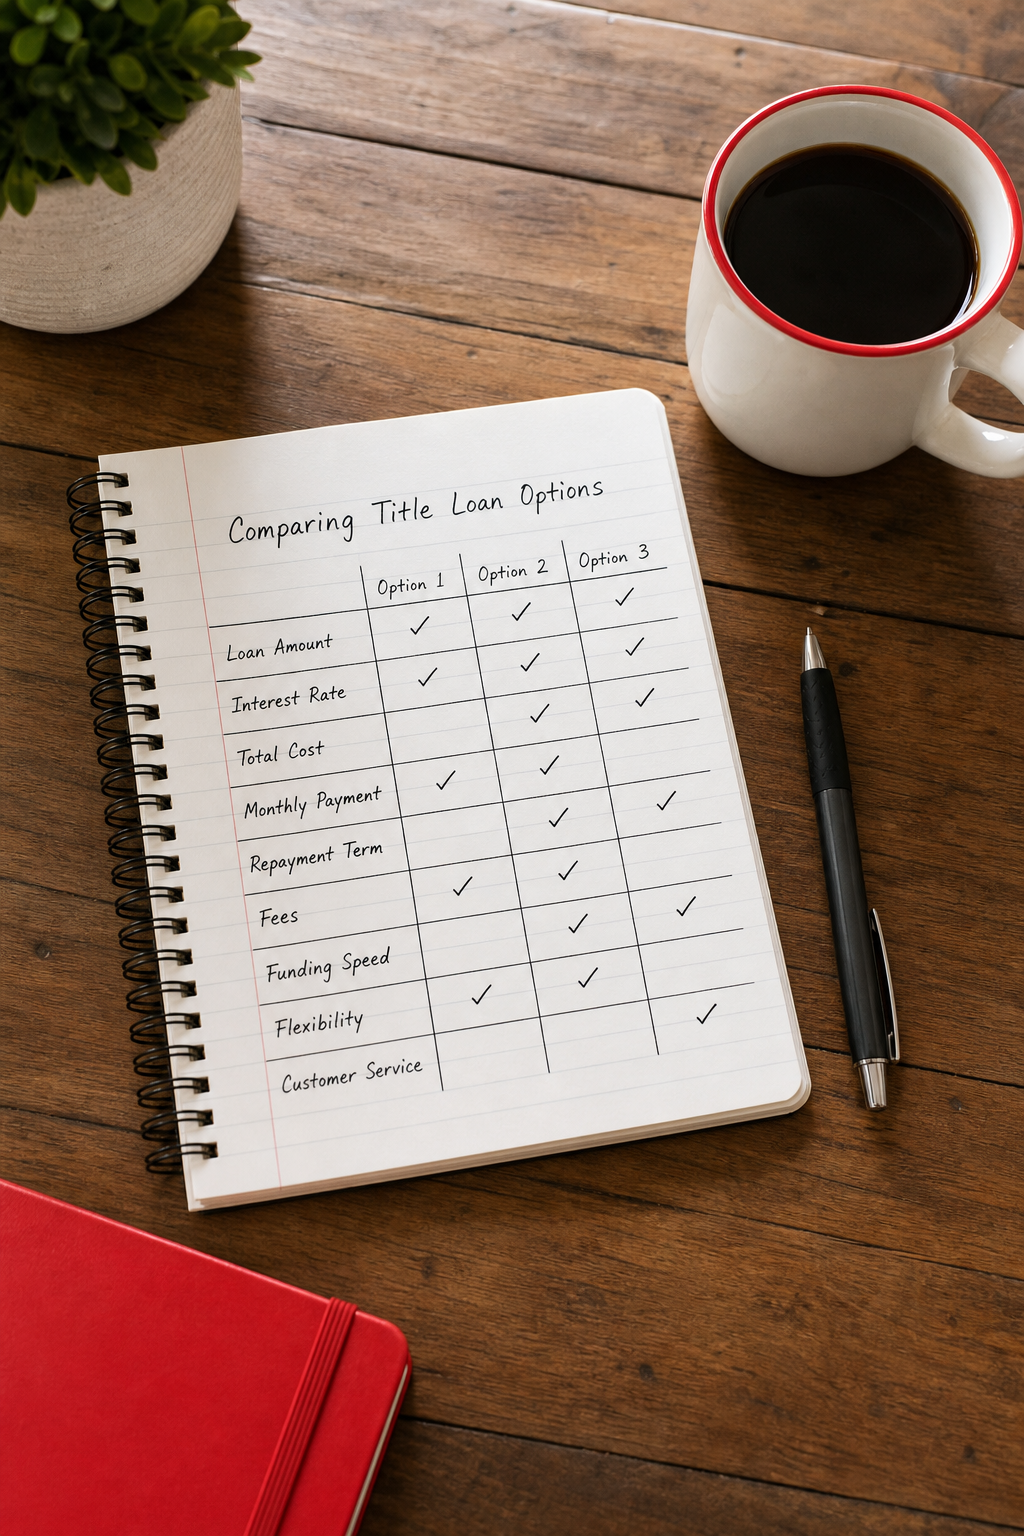
Picking a title loan comes down to four things: rate transparency, loan amount relative to your vehicle’s value, repayment term length, and state eligibility. Here’s how to work through each one.
Check APR disclosure first.If a lender won’t tell you the APR before you apply, that’s a signal. Our research found most lenders in this market have high APRs, often exceeding typical loan rates. Get the number in writing.
Know your vehicle’s value.Most lenders offer a portion of your car’s current market value. A typical pickup might qualify for a loan amount based on a portion of its value, depending on condition and state rules. Check your state’s regulations before applying, since some states cap loan amounts relative to income or vehicle value.
Look at the repayment window.A 30-day term is very different from a 12-month term. Short terms mean a large lump‑sum payment is due fast. Longer terms spread payments out but may cost more in total interest. EZ Car Title Loans, for example, offers terms from 91 days to 70 months, which is wider than most competitors.
Verify state eligibility.Title loans are legal in many states. Some states have strict caps on rates or loan amounts. Others allow lenders to operate with minimal restrictions. If you’re in Texas, regulations differ significantly from other states; lenders there operate as Credit Access Businesses under state‑specific rules. For a deeper look at how Texas rules work, the EZ Car Title Loans Texas guide covers lender caps and local ordinance limits in detail.
Managing multiple financial obligations at once, a title loan, insurance, and household expenses, takes planning. Borrowers who also carry property‑related costs like homeowners or renters insurance may find it useful to review those expenses alongside loan payments. A resource like renters insurance cost comparisons can help identify where to trim fixed costs while repaying a short‑term loan.
Comparison Table: Key Features Across Top Title Loan Providers
FAQ
What do title loan reviews say about APR rates?
Most title loan reviews indicate that APR rates vary widely, and some lenders charge well above average. Our research found only a few lenders publicly disclose their APR range. EZ Car Title Loans indicates that APRs can be lower than many competitors, but exact rates depend on the lender and borrower qualifications. Always ask for the APR in writing before signing anything.
Can I get a title loan with bad credit?
Yes. Most title lenders don’t run a traditional credit check. Approval depends mainly on your vehicle’s equity and your ability to repay. That said, title loans don’t report payments to credit bureaus, so they won’t help you build credit. If bad credit is your situation, compare the total loan cost against other options like credit union secured loans before committing.
How much can I borrow against my car title?
Lenders typically allow you to borrow a portion of your vehicle’s current market value. If your car is worth $10,000, you might qualify for a loan in the low‑to‑mid thousands. Some platforms like EZ Car Title Loans work with lenders who may offer higher amounts for high‑value vehicles. Your state’s regulations may also cap the loan amount relative to your income or the vehicle’s retail value.
Are title loans legal in my state?
Title loans are legal in many U.S. states, though some states prohibit them or impose strict limits. State rules also vary on rate caps, loan amount limits, and repayment terms. Check your state’s financial regulator website or confirm directly with the lender before applying.
What happens if I can’t repay a title loan?
If you default, the lender has the legal right to repossess your vehicle. Some lenders offer rollover options that extend the loan, but these add fees and can trap you in a cycle of rising debt. If you’re struggling to repay, contact the lender early. Acting before you miss a payment gives you more options than waiting until the lender initiates repossession.
Is EZ Car Title Loans a direct lender?
No. EZ Car Title Loans is a broker that connects borrowers with licensed lenders. That means your actual rate, loan amount, and terms come from the lender you’re matched with, not from EZ Car Title Loans directly. The broker model can surface multiple offers, and APRs vary by lender and state.
Conclusion
nn
If you’re comparing title loan options, start with a provider that publishes its APR before you apply. EZ Car Title Loans does that, and its longer repayment terms and broker model make it the strongest starting point for most borrowers. Visit EZ Car Title Loans to start your application and see what lenders in your state can offer based on your vehicle’s value.


