

json
{ “Title”: ” Title Loan with No Income Proof: What to Know”, “MetaDescription”: “Learn how title loans work without income proof, what lenders actually require, typical terms, state rules, and how EZ Car Title Loans can help.”, “article_html”: “
Getting a title loan when you don’t have a traditional paycheck is possible, but the rules are murkier than most lenders let on. Most lenders that market themselves as “no income proof” keep their actual verification policies hidden, which leaves borrowers chasing answers they should have upfront.
nn
Understanding Title Loans Without Income Verification
A car title loan is a short-term secured loan. You hand over the title to your vehicle as collateral, borrow a percentage of the car’s value, and keep driving while you repay. Because the car backs the loan, lenders care less about your credit score and more about whether your vehicle has enough equity.
Income verification is a different question. When a lender asks for proof of income, they want to know you can actually repay. But “income” doesn’t have to mean a W-2 paycheck. Many lenders accept a wide range of documents as evidence of repayment ability.
Common alternatives to a pay stub include:
- Social Security or disability benefit letters
- Pension or retirement account statements
- Bank statements showing regular deposits
- Annuity payment records
- Unemployment benefit documentation
- Settlement or court-ordered payment agreements
- Freelance invoices or PayPal/Venmo transaction history
Severance pay also counts at many lenders. If you were recently laid off and received a lump-sum severance, that can serve as documented income for a loan application. The same logic applies to rental income, investment distributions, and workers’ compensation payments.
Many lenders do not clearly disclose their income‑verification requirements, making it difficult for borrowers to know exactly what documentation is needed. Lenders are quick to advertise no credit check, but they rarely spell out what they actually need from you on the income side.
Lenders are required under federal law to disclose the finance charge and APR in writing before you sign. This gives you the right to see the full cost before committing.
Disclaimer: EZ Car Title Loans is not a direct lender and does not set APRs or loan terms. Rates and terms vary by lender and state, and failure to repay can result in vehicle repossession.
How EZ Car Title Loans Handles Income Proof Requirements
EZ Car Title Loans is a loan-matching platform, not a direct lender. That distinction matters. It connects vehicle owners with licensed title loan lenders across multiple U.S. states, and the terms, APR, and income requirements you’ll face depend on the specific lender matched to you in your state.
What EZ Car Title Loans does make clear: a credit check is not required. Your borrowing amount is based on your vehicle’s value, not your credit score. That removes one of the biggest barriers for people who’ve had past financial trouble.
On the income side, the platform’s lenders require some form of income documentation, but the definition is flexible. You don’t need a steady paycheck to satisfy it. Social Security letters, disability award letters, bank statements, pension distributions, and self-employment records all count. The requirement is about showing you have a way to repay, not proving you have a traditional employer.
Loan amounts through EZ Car Title Loans vary based on vehicle equity and state regulations. APRs for qualifying borrowers vary widely. Repayment terms can range from short‑term to several years, with no prepayment penalties. This transparency distinguishes EZ Car Title Loans from many competitors, many of which do not publicly disclose APR ranges.
The process is straightforward. You fill out a short online form with your vehicle details and contact information. A specialist follows up to walk you through lender options and explain what documentation you’ll need. If approved, you keep driving your car throughout the repayment period. For borrowers in Ohio specifically, the guide to getting a car title loan with no income in Ohio covers state‑specific rules in more detail.
One honest caveat: because EZ Car Title Loans works with multiple lenders, the exact income documentation required will vary. Ask your assigned specialist upfront what that specific lender needs before you gather paperwork.
Typical Loan Amounts and Terms Across Major Lenders
Title loan amounts are tied directly to your vehicle’s value. Most lenders offer between 25% and 50% of the car’s current market value. So if your car is worth its market value, you might qualify for a portion of its value, typically a few thousand dollars. The vehicle’s condition, mileage, make, and model all factor in.
Among lenders with published loan ranges in our research sample, TitleBucks and TitleMate sit in the $5,000‑$6,000 range, while TitleMax and LoanMart go up to $10,000‑$15,000. EZ Car Title Loans connects borrowers with lenders that may provide higher loan amounts for qualifying vehicles, reflecting its broader lender network rather than a single in‑house product.
Repayment terms are where title loans get risky. Most standard title loans are due in 15 to 30 days. That short window is what drives borrowers into rollovers, where you pay a fee to extend the loan instead of paying it off. Each rollover adds more interest and fees, and the debt grows fast.
Title loans often carry high monthly interest rates, which can translate into very high annual percentage rates. On a small loan, total repayment can be significantly higher than the principal. That’s the math borrowers need to see before signing.
Longer repayment terms, like those available through EZ Car Title Loans’ network (up to 70 months), change the math significantly. They lower the monthly payment and reduce the pressure that pushes borrowers into rollovers. No prepayment penalties mean you can pay it off early if your financial situation improves without being charged for it.
The absence of APR disclosures across most lenders is a real problem. In the research sample for this article, not a single competitor published an APR range on their website. That makes comparison shopping almost impossible without calling each lender directly. If a lender won’t tell you the APR before you apply, that’s a red flag worth taking seriously.
State‑by‑State Eligibility and Regulations
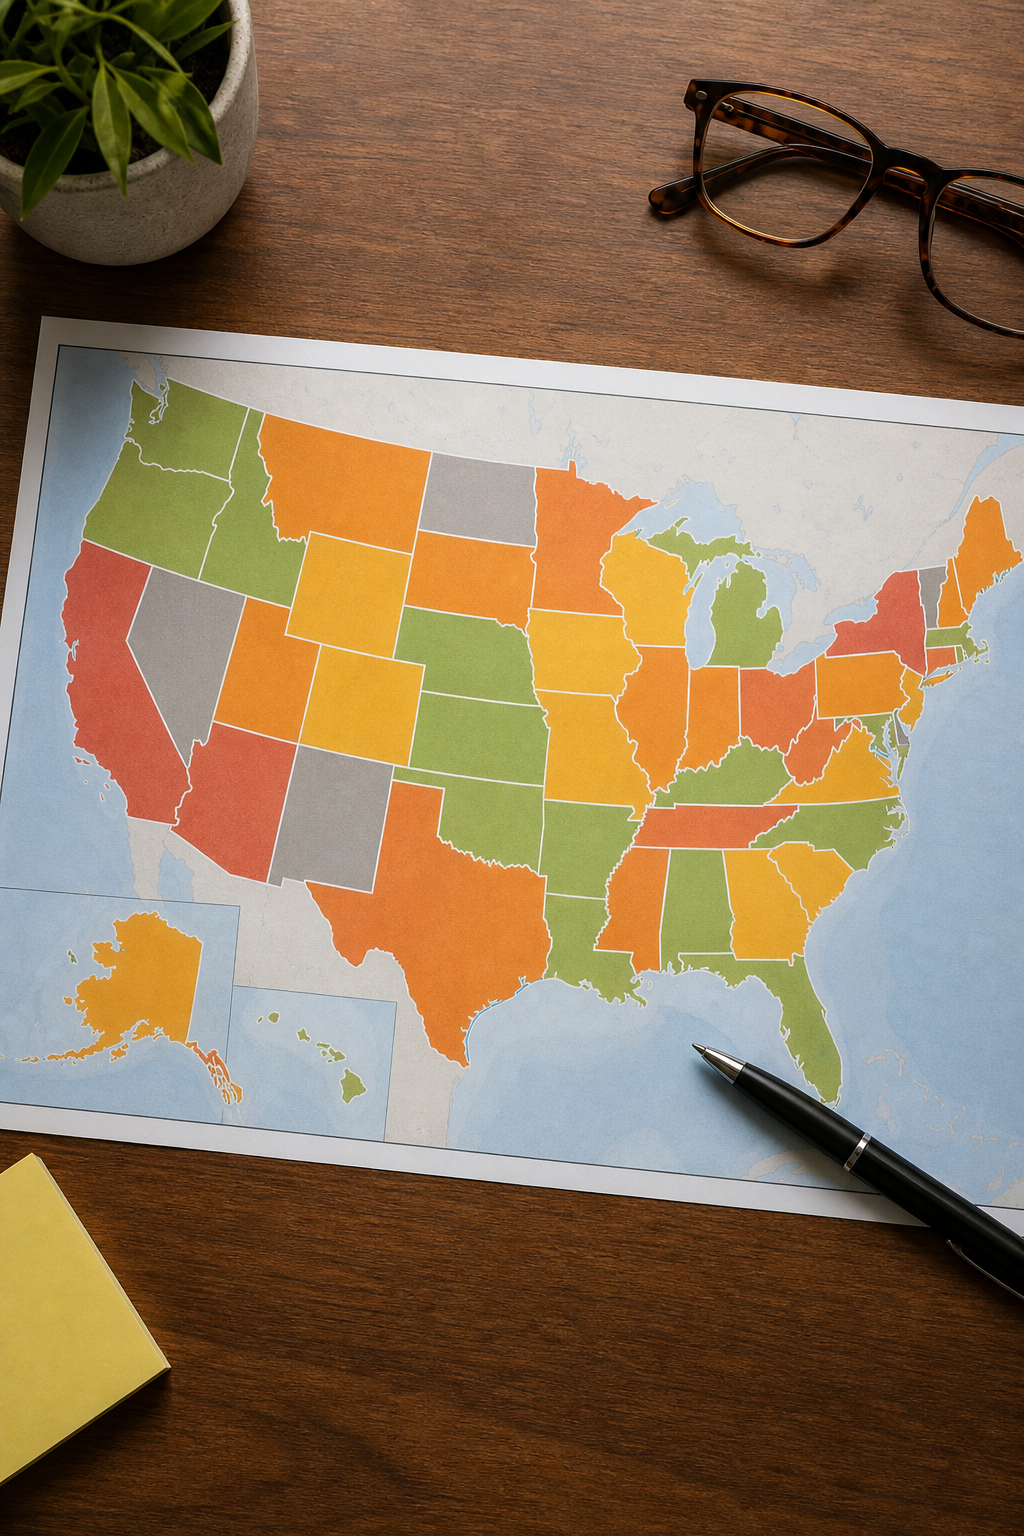
Title loans are not legal in every state. They’re permitted in roughly 27 states, and the rules vary widely even among states where they’re allowed. Some states cap interest rates. Others require specific licensing for lenders. A few states technically ban title loans but allow lenders to operate through loopholes by structuring the product differently.
State coverage among major lenders is uneven. Check N Title Loans operates only in Texas. Check City lists 13 specific states including California, Nevada, Utah, and Missouri, among others. LoanMart claims presence in around 30 states. EZ Car Title Loans notes coverage across multiple U.S. states, with the exact lender availability depending on where you live.
If you’re in the military, the rules are different. The Military Lending Act caps the Military Annual Percentage Rate at 36% for covered loans, which includes most car title loans. That cap applies regardless of what state you’re in, and lenders are required to disclose it. Borrowers on active duty should confirm their loan is covered before signing.
Consumers should check with their state attorney general or state financial regulator before applying for any title loan. Unlicensed lenders don’t have to follow local rate caps, and some operate in states where title lending is technically restricted by structuring their products as something else. Your state regulator’s website will list licensed lenders and flag known bad actors.
When it comes to protecting other assets while you sort out a financial crunch, it’s worth knowing what your existing insurance covers. A resource like this guide on what renters insurance covers can clarify whether your personal property has any protection during a difficult period, which is a separate but related financial consideration.
Income requirements also vary by state. Some states allow lenders to skip income verification entirely because the vehicle serves as full collateral. Others require lenders to assess repayment ability as part of consumer protection rules. This is one more reason to ask your specific lender what their state requires, rather than assuming “no income proof” means the same thing everywhere.
Comparing Popular Title Loan Providers (Including EZ Car Title Loans)
The table below summarizes what’s publicly known about the major title loan providers in this space. Where data wasn’t published by the lender, the field is marked with a dash. Use this as a starting point, then verify current terms directly with any lender you consider.
The pattern in that table highlights a transparency gap. EZ Car Title Loans provides some APR information, while other lenders typically require a direct conversation to learn loan costs.
EZ Car Title Loans also stands out on repayment terms. The 91-day to 70-month window is far longer than the 15-to-30-day standard most title lenders use. That flexibility matters. A shorter loan term at 300% APR is structurally harder to repay than a longer-term installment loan at a disclosed rate, even if the monthly number looks lower on paper.
For borrowers who want to avoid repossession risk, the no-prepayment-penalty policy is worth noting. If you get back on your feet financially and want to pay off the loan early, you won’t be penalized for it. That’s not a given across the industry.
One thing every borrower should do before applying anywhere: verify the lender is licensed in your state. Your state attorney general’s website lists licensed lenders and any enforcement actions. An unlicensed lender has no obligation to follow state rate caps or consumer protection rules.
FAQ
Can I get a title loan with no job at all?
Yes, in many cases. Title loans are secured by your vehicle’s equity, so lenders focus on the car’s value rather than your employment status. You’ll still need to show some ability to repay, but that can come from Social Security, disability benefits, pension income, rental income, or bank statements showing regular deposits. Some lenders skip income verification entirely if the vehicle equity is strong enough.
What documents do I need if I don’t have pay stubs?
Without pay stubs, you can typically use Social Security or disability benefit letters, pension or retirement account statements, bank statements showing consistent deposits, annuity payment records, or freelance income documentation like invoices or payment app history. The specific documents accepted vary by lender and state, so confirm with your lender before applying.
How much can I borrow against my car title?
Lenders typically base the loan amount on a portion of your vehicle’s market value, allowing you to borrow against the equity you have. The exact amount you can receive varies by lender, vehicle equity, and state regulations. EZ Car Title Loans connects borrowers with lenders, and loan amounts depend on these factors.
Are title loans legal in my state?
Title loan legality varies by state. Some states allow them, while others impose bans or strict restrictions. Before applying, check with your state attorney general or financial regulator to confirm whether title lending is permitted where you live and whether the lender you’re considering is licensed in your state.
What happens if I can’t repay a title loan?
If you default, the lender can repossess and sell your vehicle. In some states, lenders keep any sale proceeds that exceed what you owe. Rolling over the loan extends the deadline but adds fees and interest, making the debt grow quickly. If you’re struggling to repay, contact your lender early. Some will work out a modified payment plan before moving to repossession.
Does applying for a title loan hurt my credit score?
Usually not. Most title lenders don’t run a hard credit inquiry when you apply, so your credit score typically isn’t affected. However, title lenders also don’t report your on-time payments to credit bureaus, which means the loan won’t help you build credit either. Some lenders do a soft identity check, which doesn’t affect your score.
Conclusion
nn
A title loan without traditional income proof is genuinely available, but the details matter. Most lenders won’t tell you their income policies or APR ranges unless you ask directly. EZ Car Title Loans is the clearest option in this space: published APR range, flexible income documentation, no credit check, and repayment terms that give you room to breathe. If you own a vehicle with a clear title and need fast access to cash, start by submitting a free application at EZ Car Title Loans to see what your car qualifies for with no obligation.


