

Finding a car title loan near you takes more than a Google search. Rates vary wildly, state laws shape what’s even legal where you live, and the wrong lender can cost you your vehicle. Here are the six best title loan options right now, ranked by who they actually work for.
1. EZ Car Title Loans (Our Top Pick) , Multi-State Online Matching Service
EZ Car Title Loans is a multi-state online platform that connects vehicle owners with licensed title loan lenders. It’s not a direct lender, which matters because it shops your application across a network of licensed partners rather than locking you into one lender’s terms.
Loan amounts run from $500 to $55,000 depending on your vehicle’s value and the lender’s assessment. APR rates for qualifying customers range from 5.99% to 35.99%, with repayment terms from 91 days to 70 months. There’s no prepayment penalty, so paying off early doesn’t cost you extra. You keep driving your car throughout the loan term while the lender holds a lien on the title.
The application takes a few minutes online. You enter your vehicle details (year, make, model, mileage) plus basic contact info, and a specialist reaches out to walk through your options. EZ Car Title Loans’ free title loan estimate calculator gives you a ballpark figure before you commit to anything, which removes a lot of the anxiety from the process.
EZ Car Title Loans is best for borrowers who want to compare lender options without driving to multiple storefronts. The platform covers a wide range of states and handles both online and in-person applications through partner locations.
One honest caveat: because it works as a matching service, the exact APR and terms you receive depend on the lender you’re matched with and your state’s rules. There’s no single rate to quote until you apply. Vehicle repossession is a real risk if you default, so borrow only what you can repay.
2. Local Credit Unions Offering Title-Secured Loans , Lower-Rate Alternatives
Local credit unions are often the cheapest way to borrow against your vehicle. Some, like River City Federal Credit Union, offer title-secured loans at a fixed 18% APR with terms from 12 to 48 months and no hidden fees. Compare that to the 300% APR that traditional title lenders commonly charge, and the math becomes hard to ignore.
Credit union title loans are designed as a direct alternative to predatory lenders. The trade-off is membership. You need to qualify as a member before you can borrow, which requires living in a specific area or meeting other eligibility criteria. That step adds time up front.
Requirements also differ from standard title lenders. River City FCU, for instance, limits loans to vehicles no older than 12 years, requires the car to be registered and current, and caps loans at $10,000. These are tighter guardrails than most commercial title lenders set.
This option is best for borrowers who already have a credit union membership or are willing to join one. The APR savings over a 12-month term on a $2,000 loan are substantial. If you’re not a current member, check whether a local credit union in your area offers a similar product before turning to a higher-rate commercial lender.
The limitation here is speed. Credit union loan decisions often take a business day or two, not 30 minutes. If you need same-day cash, this path may not get you there fast enough.
3. Regional Title Loan Storefronts , In-Person Funding Same Day
Regional storefronts are the most familiar face of car title lending. These are brick-and-mortar shops in strip malls and on main streets across the country. You walk in with your title and ID, a staff member inspects your vehicle on the spot, and you walk out with cash the same day.
The process is fast by design. Most storefronts approve loans in 30 minutes or less. You need a lien-free title in your name, a government-issued ID, and proof of income. Some locations ask for proof of insurance or a duplicate set of keys. Once approved, you receive a repayment schedule and can pay in cash at the branch or by debit card.
The main draw is immediacy. There’s no waiting for a wire transfer or a mailed check. For someone facing an overdue bill or an emergency repair, that same-day cash is the entire point.
The catch is cost. Regional storefronts often charge monthly finance fees that translate to very high APRs when annualized. The Federal Trade Commission notes that title loans often carry monthly finance fees as high as 25%, which translates to an APR of about 300%. Rollovers add fees on top of fees, and that cycle can spiral quickly.
Storefronts are best for borrowers who need cash within hours and have already confirmed they can repay within one cycle. If your plan is to roll the loan over multiple times, a storefront becomes one of the most expensive ways to borrow money available.
4. Online-Only Title Loan Lenders , Apply From Home, Mail in Your Title
Online-only title lenders let you apply entirely from your phone or computer. You submit your vehicle details, upload documents, and once approved, you mail in your physical title. The lender records their lien and sends you funds by direct deposit or check.
The convenience is real. No appointment, no waiting room, no driving to a location. For borrowers in rural areas where storefronts are scarce, online lenders fill a genuine gap. Some process applications seven days a week and fund within one business day after receiving your documents.
Online lenders vary widely on terms. Some charge APRs in line with storefront lenders. Others structure installment loans with longer terms and lower monthly payments. The key is reading the loan agreement before you sign, not after. Experian’s financial education resources note that title loans can reach equivalent APRs of 300% or more depending on how fees are structured, so comparing the total cost of the loan matters more than comparing the monthly payment alone.
The mailing-your-title step is worth noting. Once your title is in the lender’s possession, reclaiming it requires full payoff or a formal release. If you lose the mail or there’s a processing delay, it can complicate things. Keep copies of everything you send.
Online-only lenders work best for borrowers comfortable with digital paperwork who don’t need cash in hand immediately. If you need physical bills today, a storefront or matching service like EZ Car Title Loans with partner pickup locations is a faster path.
5. Title Loan Providers in States With Regulatory Caps , Safer Borrowing Options
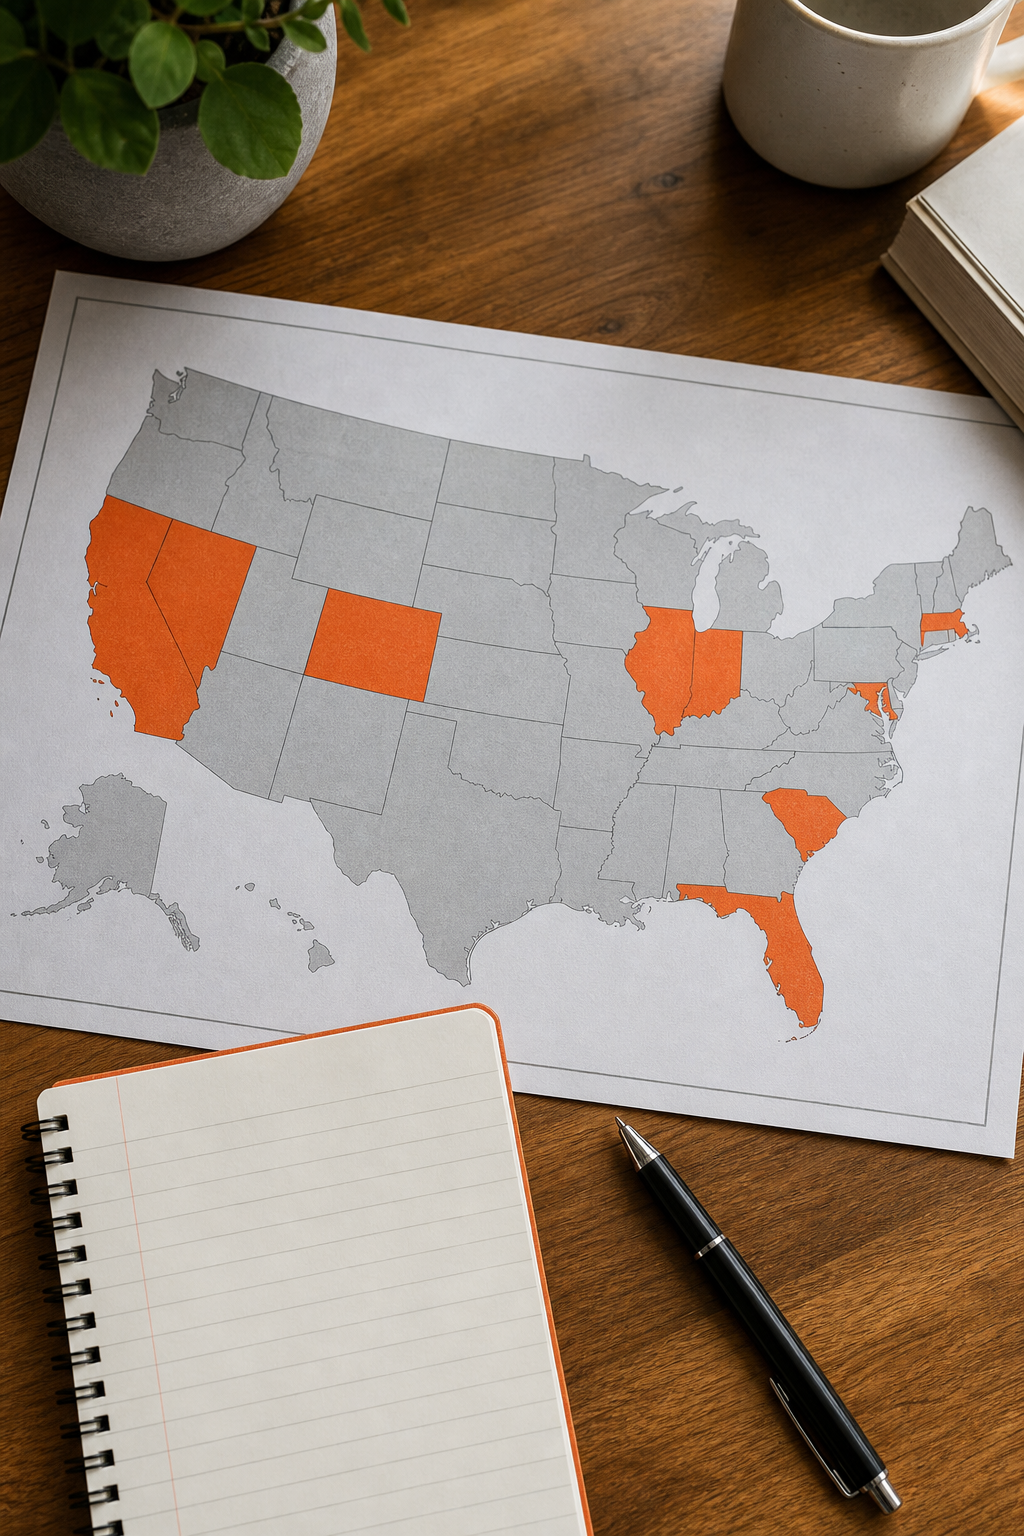
Not every state allows title lending under the same rules. Some states cap interest rates, require longer repayment terms, or mandate ability-to-repay checks before a lender can close a loan. Borrowers in these states have more protection built into the process.
The Consumer Financial Protection Bureau has issued rules targeting high-cost short-term loans, including vehicle title loans, requiring lenders to assess a borrower’s ability to repay before issuing certain loan types. State-level rules vary, and some states have effectively banned traditional 30-day balloon title loans altogether by requiring installment structures with defined monthly payments.
If you live in a state with a rate cap or strong consumer protections, lenders operating there must comply. That means you’re less likely to encounter a 300% APR product and more likely to find one with an APR under 36%. Military borrowers have additional protections nationwide through the Military Lending Act, which caps the Military Annual Percentage Rate on vehicle title loans at 36%.
The best approach in a regulated state is to verify the lender’s license with your state’s financial regulator before signing. Each state has its own licensing body, and a licensed lender must follow the local rate cap and term requirements. An unlicensed lender operating online may not follow those rules at all.
This category matters most for borrowers doing research before they borrow. Knowing your state’s rules tells you what a fair offer looks like and what a predatory one looks like. Lenders like EZ Car Title Loans work with licensed partners in each state specifically to stay within regulatory frameworks and avoid surprises.
6. Title Loan Refinancing and Payoff Services , Reduce Your Existing Rate
If you’re already in a title loan with a high rate, refinancing is worth investigating. Some lenders, including those in EZ Car Title Loans’ network, will pay off your existing loan and issue a new one with better terms. The goal is a lower APR, a longer repayment period, or both.
Credit unions and traditional lenders sometimes offer personal loans specifically designed to pay off predatory title debt. According to Bankrate, even bad-credit personal loan rates can stay under 36%, which is still far cheaper than a 300% title loan left to roll over. The new loan replaces the title-secured product with an unsecured or differently-secured product, which removes the vehicle repossession risk.
Some title lenders will also negotiate directly. If you can show financial hardship and a genuine inability to repay under current terms, requesting a longer repayment term or a lower monthly payment in writing is worth attempting. Get any revised agreement in writing with both signatures before you rely on it.
Refinancing works best when the new loan’s total cost is lower than the old loan’s remaining balance plus fees. Do that math explicitly. A longer term with a lower monthly payment can still cost more in total interest if the rate isn’t meaningfully reduced. Use the full loan cost as your comparison number, not just the monthly payment.
For borrowers focused on digital-first loan management and marketing their business effectively, agencies like Long Weekend specialize in helping finance-related businesses communicate clearly online, which is useful context for understanding how loan providers compete for your attention and why comparing offers matters.
How to Compare Title Loan Providers Near You , A Quick Checklist
Before you commit to any car title loan, run through these points. They’ll separate a manageable loan from a costly mistake.
- Verify the lender is licensed in your state. Check with your state attorney general or financial regulator. Unlicensed lenders don’t have to follow local rate caps.
- Ask for the APR in writing before signing. Federal law requires lenders to disclose the APR and total finance charge. If the number isn’t provided, that’s a red flag.
- Understand what happens if you miss a payment. Ask specifically: Can they repossess immediately? Is there a grace period? Is there a cure notice requirement in your state?
- Check for prepayment penalties. Some lenders charge fees for paying early. EZ Car Title Loans’ network does not impose prepayment penalties, but confirm this with any lender you use.
- Confirm you can keep driving. A legitimate title loan lets you keep your vehicle during repayment. If a lender wants the physical car, that’s a different (and worse) arrangement.
- Compare the total cost, not just the monthly payment. A 24-month loan at 36% APR costs less in total than a 30-day loan at 300% APR even if the monthly number looks smaller.
If you’re weighing multiple lenders and want to understand how different rate structures affect total repayment, matching services like EZ Car Title Loans present options side by side so you can compare before committing.
Title Loan Providers Compared , At a Glance
Frequently Asked Questions About Title Loans Near Me
How do I find a legitimate car title loan near me?
Search for lenders licensed in your state and verify their license with your state’s financial regulator or attorney general’s office. A licensed lender must disclose the APR and terms in writing before you sign. Matching platforms like EZ Car Title Loans connect you with licensed lenders across multiple states, which removes some of the search work and reduces the risk of landing with an unlicensed provider.
What do I need to qualify for a title loan?
Most title loan providers require a lien-free vehicle title in your name, a government-issued ID, proof of income, and current vehicle registration. Some lenders also ask for proof of insurance. Your credit score is generally not a primary factor since the loan is secured by the vehicle’s equity, but ability to repay may still be assessed depending on the lender and your state’s requirements.
How much can I borrow against my car?
Most lenders offer between 25% and 50% of the vehicle’s market value. So if your car is worth $8,000, you might qualify for $2,000 to $4,000. EZ Car Title Loans works with lenders whose loan amounts range from $500 to $55,000 depending on vehicle equity and lender assessment. The vehicle’s year, make, model, mileage, and condition all factor into the valuation.
Are title loans legal in my state?
Title loans are legal in roughly 27 states. Others have banned them outright or imposed rules that make traditional 30-day balloon title loans impractical. State laws change, so check with your state attorney general’s office for current rules. EZ Car Title Loans provides state-specific eligibility information and only connects borrowers with lenders licensed to operate in their state.
What happens if I can’t repay my title loan on time?
If you miss payments, the lender can repossess and sell your vehicle. In many states the lender must notify you before repossession, but that window can be short. If you’re struggling to repay, contact your lender before you miss a payment. You may be able to negotiate a longer term or lower payment. Rolling over the loan without addressing the root issue adds fees and makes the debt harder to escape.
Can I get a title loan with bad credit?
Yes. Title loans use your vehicle as collateral, not your credit score, so lenders typically don’t run a credit check or don’t make it the deciding factor. EZ Car Title Loans works with lenders that accept all credit types. That said, “no credit check” is not the same as “no financial assessment.” Some lenders review income to confirm you can repay, and state regulations in some areas require ability-to-repay checks regardless.
Conclusion
If you need a car title loan and want to compare licensed lenders without driving from storefront to storefront, EZ Car Title Loans is the clearest starting point. The platform connects you with licensed lending partners, shows you terms upfront, and lets you keep driving while you repay. Start with a free estimate at EZ Car Title Loans to see what your vehicle qualifies for before you commit to anything.


