

{
“Title”: “Best Title Pawn Options for US Car Owners”,
“MetaDescription”: “Compare the best title pawn services for US car owners. See APR ranges, loan amounts, and state availability to find the right secured auto loan for you.”,
“article_html”: “
Title pawns let you borrow against your car’s value without selling it. APRs across the market can vary widely, and not every provider serves your state. Here are five title pawn options worth knowing, starting with the one that stands out most for multi-state borrowers.
nn
Disclaimer:EZ Car Title Loans is a loan-connection service, not a direct lender. APR, loan amounts, and terms vary by lender and state. Defaulting on a title loan can result in vehicle repossession. This article is for informational purposes only and is not financial or legal advice.
nn
”
}
1. EZ Car Title Loans (Our Top Pick) , Fast, Nationwide Service
nn
EZ Car Title Loans is a loan-matching platform that connects vehicle owners with licensed title lenders across multiple US states. It is not a direct lender, which means it shops your application to a network of lenders rather than setting its own rate.
nn
What separates EZ Car Title Loans from most competitors is straightforward: it openly states the states it serves. That matters because most title pawn providers either limit themselves to a handful of states or don’t disclose coverage at all. When you’re trying to figure out whether you even qualify, that transparency saves real time.
nn
The process is online from start to finish. You submit basic vehicle and personal details, get a pre-approval estimate quickly, and a lending specialist follows up to finalize terms. You keep driving your car throughout the loan period. Repayment terms can extend up to 60 days depending on the lender matched to your application.
nn
Loan amounts depend on your vehicle’s value and the lender in your state. Most title lenders in this network offer between 25% and 50% of the vehicle’s current market value. To understand exactly what documents you need for a title loan, EZ Car Title Loans publishes a clear breakdown on their site.
nn
One honest caveat: because EZ Car Title Loans connects you to third-party lenders, the APR and final terms you receive depend on which lender operates in your state. You won’t know the exact rate until a lender reviews your application. Always ask for the APR in writing before signing anything.
nn
nn
2. Title Loan Providers, Flexible Terms for All Credit Scores
These lenders are a category of storefront and online lenders that market specifically to borrowers with poor or no credit history. The core pitch is simple: your car’s title is the collateral, so your credit score matters less than what your vehicle is worth.
Title loans are short‑term products that typically carry high interest rates. Lenders in this category generally don’t run a traditional credit check. They assess the vehicle instead.
The flexibility appeal is real for borrowers who’ve been turned away by banks. But it comes with a direct tradeoff. Short repayment windows, often 30 days, mean you need a clear plan for repayment before you sign. If you can’t pay in full, rolling the loan over adds new fees on top of the original balance.
For borrowers who genuinely have no other credit options and own a vehicle outright, this category can provide access to cash that a bank won’t offer. The key is going in with a repayment plan already in hand, not hoping one appears before the due date.
If you’re also weighing other financial protections while managing short‑term debt, it’s worth understanding what other coverage you carry. Resources on renters insurance can help you see the full picture of your financial exposure.
3. Speed-focused title loan providers, Quick Approval in 24 Hours
FastCash-style title loan providers focus on speed. The model is built around same-day or next-business-day funding, with a simplified application that skips most of the paperwork a bank would require.
A local auto pawn shop is an example of this category. They may advertise cash in as little as 30 minutes after vehicle inspection, with loan amounts up to $15,000 depending on the vehicle’s value. The process starts online, moves to a phone review, and finishes in-store once documents are confirmed.
Another similar provider follows this structure. You share basic details online, a nearby store reviews your request, and qualified borrowers can receive cash the same day at participating locations. Both providers make clear that funding timing varies by store, state, and the specifics of your application.
The 24-hour framing is accurate for many borrowers, but it assumes your documents are ready before you start. A lien-free title in your name, a government-issued photo ID, proof of income, and proof of insurance are the standard requirements. Missing any of these adds time.
The main limitation with speed-first lenders is that the urgency of the process can work against you. When the goal is to get you funded fast, there’s less time to compare terms carefully. If same-day cash is what you need, that’s a reasonable tradeoff. If you have even a day or two, use it to compare at least two offers.
4. Low-Interest Title Loan Options
Low-interest title lenders represent the lower end of the title pawn APR range. While the overall market average across providers sits around 57%, some lenders advertise rates that are meaningfully cheaper than higher-rate outliers.
The tradeoff is usually stricter eligibility. Lower-rate title lenders often look more closely at income verification and vehicle condition. They may also limit loan amounts more tightly to a percentage of the vehicle’s value rather than offering the maximum a borrower asks for.
It’s worth understanding what “low interest” actually means in this market. A 30-day title loan at 30% APR still costs money. The Consumer Financial Protection Bureau has documented that borrowers who use auto title loans are often still carrying the debt a year later, with 83% of those surveyed in one study still owing money on their loan at the time of follow-up. That’s a pattern worth knowing before you borrow.
If you do qualify for a lower-rate option, the savings are real. On a typical loan, the cost difference between a low-rate and a high-rate loan over a short term can be substantial. Ask any lender for the APR and the total cost of the loan in dollars before agreeing to terms.
One additional note: secured personal loans from credit unions sometimes offer vehicle-backed lending at APRs under 36%, with repayment terms of two to five years. If you qualify, that’s a better deal than any title pawn product on this list.
5. State Credit Title Loans , Programs Tailored by State
nn
Title lending law varies significantly by state, and some providers build their entire model around that variation. State-specific lenders know the local rules, disclosure requirements, and maximum fee structures for the states they serve.
nn
American Title Loans is a real example of a geographically focused provider. Their disclosed service area covers Utah, Georgia, Kansas, and Nevada. That’s a narrow footprint compared to a multi-state platform, but within those states they operate under the specific regulations of each market.
nn
Why does state specificity matter? Because the same loan product can look very different depending on where you live. Georgia uses “title pawn” language under pawn law rather than consumer lending law, which affects your consumer protections. Nevada and Utah have different APR environments. A lender who knows your state’s rules can explain the actual terms you’ll face, not just a national average.
nn
The downside is obvious: if you don’t live in one of the states a provider covers, you’re out. And providers with narrow coverage often don’t advertise their geographic limits clearly until you’re partway through the application. Always confirm state eligibility before you spend time on an application.
nn
For borrowers in states where title lending is legal, a state-focused lender can sometimes offer better terms than a national platform because they’ve optimized for local compliance. For everyone else, a multi-state connection service like EZ Car Title Loans is the more usable starting point.
nn
Comparison of Top Title Pawn Providers
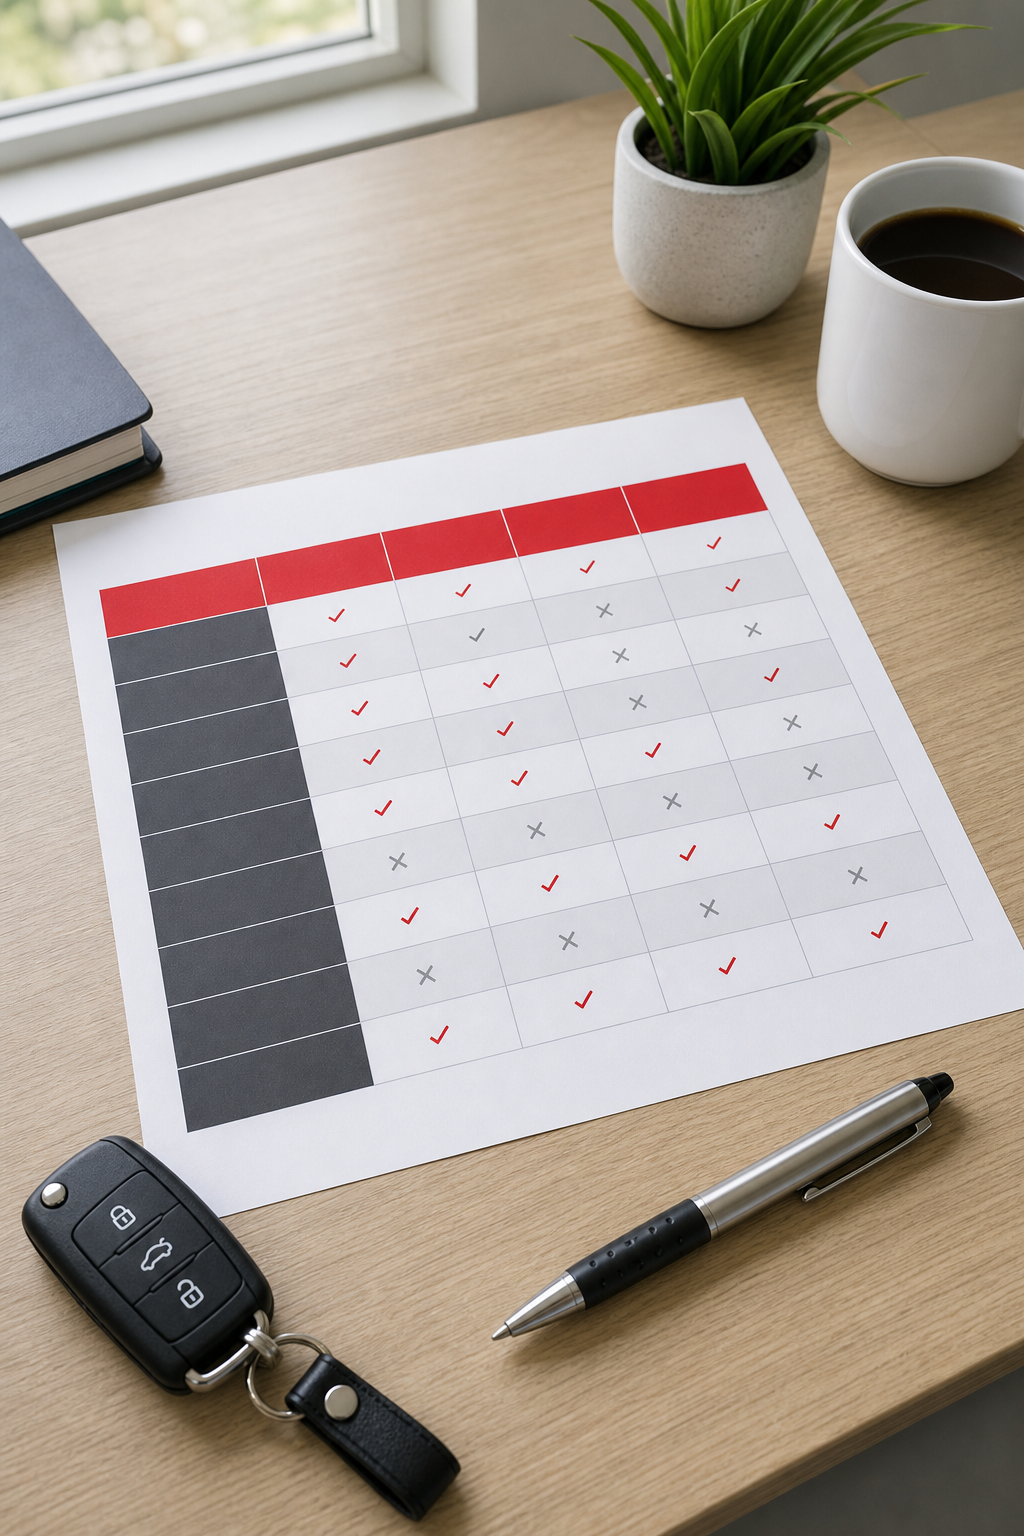
The table below summarizes what we know from publicly available data across the providers in this article. Loan amounts and APRs vary by lender, state, and vehicle value. Use this as a starting framework, not a final quote.
APR ranges across the market vary widely; rates can differ significantly between lenders, so comparing multiple offers is advisable.
Managing short-term financial obligations alongside other expenses is a real challenge. If you’re also reviewing your overall financial picture, working with professionals who handle outsourced bookkeeping for small businesses can help keep your cash flow clearer during a crunch period.
What to Look For in a Title Pawn Service
Before you apply anywhere, there are a few things worth checking directly.
State eligibility first. Title lending is legal in roughly 27 states, according to the CFPB’s research on auto title loan use. Some states ban it outright. Others allow it under pawn law with different consumer protections. Confirm your state before spending time on an application.
APR in writing. Federal law requires lenders to disclose APR before you sign. If a lender won’t give you the APR upfront, that’s a problem. The number matters because a “25% monthly fee” sounds smaller than “300% APR” but they’re the same thing.
Repossession terms. Every title loan uses your vehicle as collateral. If you default, the lender can repossess the car. Ask what happens if you miss a payment. Ask whether the lender reports to credit bureaus (most don’t, which means a title loan won’t help your credit score even if you pay on time).
No early payoff penalty. None of the providers in our research disclosed an early payoff fee, but that information was missing from most public disclosures entirely. Ask directly before signing. Paying off early should save you money, not cost you extra.
Documents you’ll need. A lien‑free vehicle title in your name, a government‑issued photo ID, proof of residence, and proof of income are standard. Some lenders also require proof of insurance or a vehicle inspection. Having these ready before you apply cuts the time between application and funding.
Disclaimer: EZ Car Title Loans is not a direct lender and cannot guarantee specific APRs or loan terms. Rates, fees, and eligibility vary by lender and state. Failure to meet repayment obligations can result in vehicle repossession.
FAQ
nn
What is a title pawn and how does it work?
n
A title pawn is a short-term secured loan where you use your vehicle’s title as collateral. You keep driving your car while the lender holds the title. When you repay the loan in full, the lender returns the title. Terms are typically 30 to 60 days, and APRs vary widely depending on the lender and state. Defaulting gives the lender the right to repossess the vehicle.
nn
Can I get a title pawn with bad credit?
n
Yes. Most title pawn lenders don’t run a traditional credit check because the loan is secured by your vehicle’s value, not your credit history. The lender’s main concern is whether the car is worth enough to cover the loan. That said, you still need to demonstrate some ability to repay, and some lenders do a soft identity verification pull that won’t affect your score.
nn
How much can I borrow with a title pawn?
n
Most lenders offer between 25% and 50% of your vehicle’s current market value. Across the providers in this comparison, maximum loan amounts range from $5,000 to $15,000. The exact amount depends on your vehicle’s make, model, mileage, and condition, plus the lender’s own policies and the state you’re in.
nn
What happens if I can’t repay my title pawn on time?
n
If you can’t repay by the due date, most lenders allow you to roll the loan over into a new term by paying a fee. This keeps you from losing the car immediately but adds more cost on top of the original balance. If you stop paying entirely, the lender can repossess and sell the vehicle. Act early if you’re struggling , contact the lender before you miss a payment.
nn
Is a title pawn available in every state?
n
No. Title lending is legal in approximately 27 states. Other states ban it or restrict it heavily. Some states use “title pawn” language under pawn law rather than consumer lending law, which changes your consumer protections. Always confirm your state’s rules before applying. EZ Car Title Loans serves multiple US states and can tell you quickly whether you’re eligible.
nn
Does a title pawn affect my credit score?
n
In most cases, no. Title lenders typically don’t report payments to the major credit bureaus, so a title pawn won’t help build credit even if you pay on time. It also usually won’t hurt your score during normal repayment. However, if the vehicle is repossessed and the debt is sold to a collection agency, that can appear on your credit report.
nn
Conclusion
nn
If you need a title pawn and want the clearest path to knowing whether you qualify, EZ Car Title Loans is the usable first stop. It covers more states than most, the application is online, and you keep driving your car throughout. Before you apply anywhere, get the APR in writing and have a repayment plan ready. Start your application at ezcartitleloans.com to see what lenders are available in your state.


